Goal is to address deterioration in public finances caused by the election and take advantage of a more favorable Congress, argues Solange Srour
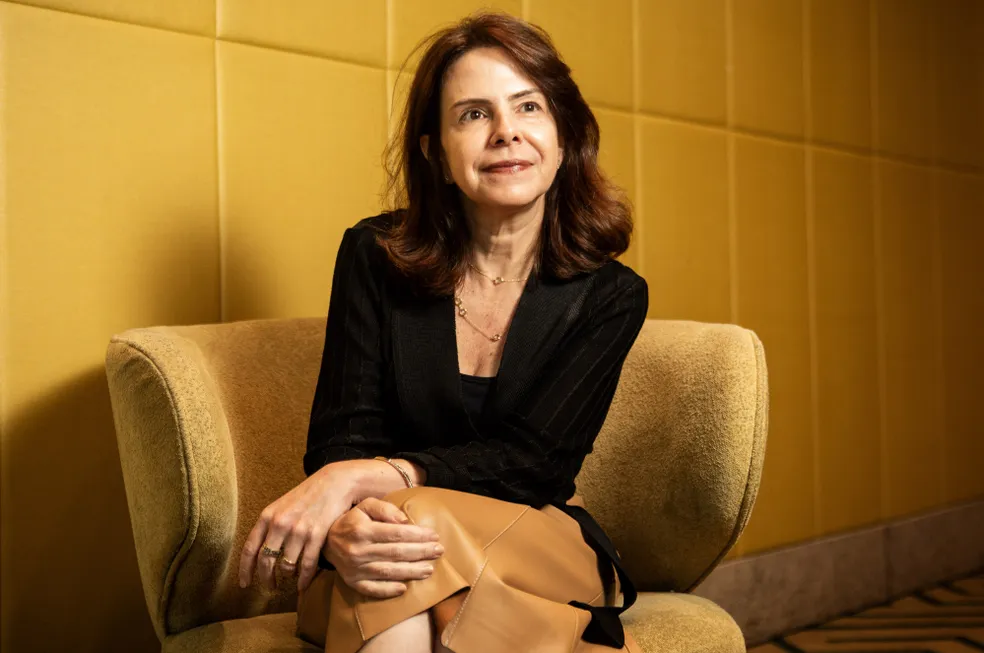
Brazil’s 2026 election campaign worsened the country’s fiscal problems and made it more urgent for the reelected president to address the issue, says Solange Srour, director of macroeconomics for Brazil at UBS GWM. In her view, Lula should announce the measures this year to take advantage of a Congress that is less opposed to his government and the good relations he has cultivated with the presidents of both chambers—advantages he may no longer have, or that could be called into question, starting next year.
Although the new legislature is more aligned with the right, it could hinder fiscal adjustment more than help it because it will require greater negotiating skills, she says. “It is easier for Congress to embrace a populist measure because, when it goes wrong, the consequences will fall into the executive branch’s lap. Spending control, by contrast, is more difficult because the government will have to negotiate with lawmakers who already wield considerable power over discretionary budget amendments,” she says.
In her view, although the campaign was marked by categorical rejections of changes to the minimum wage’s real gains, the indexation of pensions and benefits, and constitutionally mandated minimum spending on health and education, avoiding these options would be a mistake. Alternatives such as tightening the rule governing real expenditure growth—which is currently capped at 2.5%—as members of the economic team have already suggested, might avert an imminent crisis but would not deliver the credibility shock needed to bring real interest rates down more decisively.
“This middle-ground scenario would allow real interest rates to settle closer to 6.5% or 7%. That would only work under a very favorable global scenario that allowed the economy to grow considerably. Otherwise, the debt-to-GDP ratio would continue to rise very rapidly. In other words, with a middle-ground adjustment, you burn political capital to avoid a crisis but fail to escape mediocrity and remain vulnerable to new crises,” she warns.
She adds that the external environment is now fraught with considerably greater risks, including tighter monetary policy in the U.S. and an escalation of the conflict with Iran, which could put renewed upward pressure on oil prices.
Asked what profile she would like to see in the next finance minister, Srour says the key is to have someone with “an understanding that the fiscal issue is not merely a demand from the market but a macroeconomic imbalance, and who has the president’s confidence,” since the minister will need to persuade him to take tough action. “There will be some degree of electoral fraud in the political sense of breaking campaign promises. It may be greater or smaller, but without it, the crisis will approach more quickly,” she says. The following are excerpts from the interview:
Valor: The election ended with a surprising victory for President Lula. From an economic standpoint, what needs to be done now?
Solange Srour: There are several other economic issues and important reforms that need to be addressed, but fiscal reform is the priority today. This is not only because the situation we face is completely unsustainable. If nothing changes in the structural framework for mandatory spending, the debt-to-GDP ratio is very likely to grow faster than the 10-percentage-point increase recorded over the past four years, because the economy is expected to slow. But it is also because we have just gone through an election in which spending and subsidies expanded. The way the election unfolded, with Lula’s turnaround backed by popular support in the streets, makes things more difficult because, ultimately, we are saying that some degree of breaking campaign promises will be necessary. It may be greater or smaller, but without it, the crisis will approach more quickly. The situation has become even more serious.
We also have to consider that the global environment is much more challenging. Interest rates are higher worldwide, it is unclear whether the weak dollar that has greatly benefited domestic inflation will persist, and oil prices may not return to previous levels. So there is an enormous sense of urgency, but also considerable distrust, and that is what is driving markets in the aftermath of the election.
Valor: Can this package wait until 2027?
Srour: Given the makeup of Congress in 2027, I think it would be smarter for the government to try to get these measures approved now, because it has a larger support base today and very good working relationships with the presidents of the Chamber of Deputies and the Senate. In the next legislative term, much will depend on who leads the two chambers. There will be a more organized center-right bloc. If that is not the strategy, then at least there should be greater clarity about what can be done. The current climate of speculation about possible finance ministers, with no plan announced, will continue to worsen market conditions over time, with significant consequences for the economy. The worse economic conditions become, the harder it will be to announce this agenda.
Valor: Several names are already being mentioned as possible candidates for the next finance minister. Most are politicians. Do you think appointing someone from outside politics would be important to restore credibility?
Srour: I do not think that is important. What matters is having someone who understands that the fiscal issue is not merely a demand from the market but a macroeconomic imbalance, and who has the president’s confidence, because the minister will need to persuade him to take tough action, especially after so many campaign promises. It is important that the person chosen be able to attract technical experts. There are many possible fiscal adjustment proposals, not only in terms of what should be done but also how it should be done. The key is for the minister to be able to attract qualified people who can put these measures into practice. The chief of staff will also play a very important role in ensuring that the economic team has an effective political coordination arm.
Valor: Adjusting the minimum wage’s real gains, changing the indexation of pensions and benefits, and revising constitutionally mandated minimum spending on education and health are always cited as the most important fiscal adjustment measures, but both Lula and his opponent rejected them during the campaign. Is there a middle-ground measure that could satisfy the market?
Srour: I think the most likely option is that they will tighten the rule governing real spending growth, perhaps to 1.5%. That would be a middle ground between allowing spending to grow only in line with inflation and the current rule, but it would still mean breaking a campaign promise. Former minister [Fernando] Haddad himself spoke in these terms before the campaign. The big question is whether the president will accept these proposals.
Would that be enough? I believe that if it were accompanied by measures to reduce subsidies and tax expenditures, as well as higher taxation on LCI and LCA real estate and agribusiness credit instruments, it might provide some relief. But relief would mean reversing the deterioration seen in the post-election period, not achieving the lower real interest rates investors had envisioned as possible under Flávio [Bolsonaro]—if everything had gone right—at around 5.5%. This middle-ground scenario would allow real interest rates to settle closer to 6.5% or 7%.
Valor: That is still very high.
Srour: That would only work under a very favorable global scenario that allowed GDP to grow considerably. Otherwise, the debt-to-GDP ratio would continue to rise very rapidly. In other words, with a middle-ground adjustment, you burn political capital to avoid a crisis but fail to escape mediocrity and remain vulnerable to new crises. What if the Federal Reserve raises interest rates more than expected? What if oil reaches $150 a barrel?
Valor: Beyond targeting the pace of spending growth, are immediate cuts necessary?
Srour: To genuinely eliminate the risk of insolvency, the fiscal adjustment currently required is equivalent to around 4% of GDP, given prevailing market real interest rates and the level of debt. That is politically unfeasible, regardless of which candidate won the election. So what we need to do is put measures on the table that will deliver the equivalent of that adjustment over five to 10 years.
That would include redesigning Bolsa Família alongside other social programs to better target benefits, ending the indexation of the minimum wage to benefits and pensions, and reforming the social security system to raise the minimum retirement age and bring in additional sectors. When the Temer administration approved the spending cap, we saw a significant decline in interest rates. But nobody believed the spending cap alone would solve the problem. Rates fell because investors bought into the idea that a series of other reforms would make the spending cap sustainable for a considerable period. Some reforms were implemented, particularly the elimination of subsidies from the Brazilian Development Bank (BNDES), but changes were also approved to the minimum wage rule and the minimum spending requirements for education and health.
The market needs an agenda capable of stopping the rapid growth in spending. A halfway adjustment does not deliver the credibility shock; it simply avoids the worst-case scenario.
Valor: So this agenda would not worsen the already weak outlook for growth in 2027?
Srour: An economic slowdown is already locked in. This halfway agenda would simply help avert a recession, which is possible if interest rates remain at current levels and could even extend beyond 2027. On the other hand, a more robust agenda could bring real interest rates down sharply and help the economy as early as 2027.
Valor: Would a more right-wing Congress not help deliver fiscal adjustment?
Srour: I do not think so. It could be a more limiting factor because negotiations will be harder. It is easier for Congress to embrace a populist measure because, when it goes wrong, the consequences will fall into the executive branch’s lap. Spending control, by contrast, is more difficult because the government will have to negotiate with lawmakers who already wield considerable power over discretionary budget amendments.
Valor: Judicial reform was another issue that emerged during the election.
Srour: It is certainly a demand from society and influenced the first round of voting. But from an economic standpoint, institutions also need to be reformed. We talk a lot about fiscal policy, but this level of legal uncertainty and the clashes between branches of government all affect the equilibrium interest rate and investment decisions in Brazil. So this agenda may need to move forward alongside fiscal reforms, especially since many of those reforms could face legal challenges.
Valor: Could Monday’s asset price correction continue for much longer?
Srour: Markets are waiting for news, so I think it could continue, yes. If nothing is done or announced in the coming weeks, the trend is for conditions to deteriorate further. And the external environment comes into play again; it could accelerate that deterioration. There is a possibility that, after the U.S. midterm elections, [President Donald] Trump could escalate the conflict with Iran. Israel will hold elections in a week. The global environment is becoming more inflationary. And the currency appreciation that would have benefited Brazil in the event of a Flávio victory will not materialize.
Valor: How low could the Brazilian real fall, in your assessment?
Srour: If nothing happens on the fiscal front, I would not rule out the foreign exchange rate exceeding R$6 per dollar. We also need to watch what the Central Bank does at its next meeting, because high interest rates are another factor supporting the real. If the Central Bank maintains its focus on slowing economic activity, that could put some pressure on the Brazilian currency.
In the interest rate market, it is also possible that the deterioration will not stabilize. If it becomes clear that the government will offer more of the same—adjustments limited to anti-fraud measures, spending freezes, and taxation of LCI and LCA instruments—I would not rule out interest rates rising by as much as they did yesterday [Monday, 26]. If all of this happens, we could enter a fiscal dominance dynamic in which the market loses its benchmark.
*By Marcelo Osakabe — São Paulo
Source: Valor International