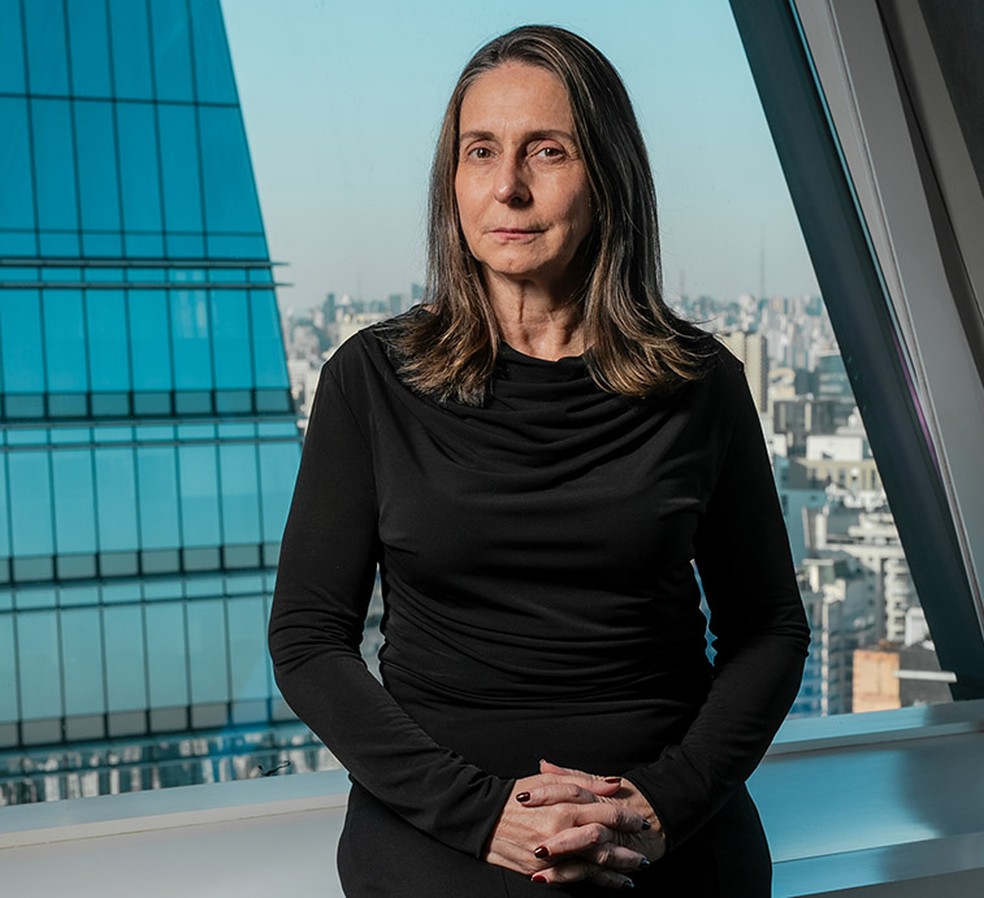
Basiliki Litvac, of XP — Foto: Keiny Andrade/Valor
Basiliki Litvac, of XP — Photo: Keiny Andrade/Valor

The international environment is emerging as a source of concern for Brazil’s efforts to control inflation in the short and medium term. In particular, economists are increasingly focused on growing threats related to oil prices and U.S. monetary policy.

These factors add to an already extensive list of domestic risks on the radar, including the impact of El Niño on food prices, the potential effects of ending the six-day workweek with one day off (known as the 6×1 schedule) on labor costs, tax reform, and the new basket of goods and services monitored by the Extended Consumer Price Index (IPCA). The basket is expected to change with the next edition of the Household Budget Survey (POF), due out at the end of this year.

Brent crude prices have returned to around $115 a barrel amid growing indications that the conflict between the United States and Iran could escalate again. President Donald Trump has signaled that he intends to pursue a short-term military campaign after the U.S. midterm elections, which begin in less than a week. Meanwhile, Israeli Prime Minister Benjamin Netanyahu, who faces a political test in elections in Israel this week, has renewed nuclear threats against neighboring Iran.

In Brazil, the impact of these shocks has been cushioned by the government’s subsidy and support programs. “The question is whether, if this conflict persists, the government will be able to maintain this policy for long given its fiscal cost. Otherwise, it would have to let prices rise, which would affect inflation,” said Julio Cesar Barros, an economist at Daycoval. His calculations show that removing the subsidies would add 0.4 to 0.5 percentage points to the IPCA.

In Buysidebrazil’s baseline scenario, which projects the IPCA at close to 4.7% in 2027, the average oil price that year is expected to fall to $85 a barrel as risks in the Middle East subside. If the reversal is less pronounced, however, the inflation estimate would be higher. A return to $100 a barrel could add 0.4 percentage points to next year’s projection, while a decline to $110 would add another 0.6 percentage points, said the consultancy’s chief economist, Andréa Damico.

“The balance of risks for the IPCA is extremely skewed to the upside. Previously, there were some disinflationary factors, such as a lower risk premium and a stronger exchange rate in the event of an opposition victory in Brazil, that could have offset all the upside risks, including El Niño and the end of the 6×1 work schedule. Now, we no longer have those counterweights,” the economist noted.

In a recent study, XP Investimentos estimates that fuel subsidies and support measures could remain in place for longer, since at oil prices above $105 a barrel, their net fiscal cost is positive.

“However, even at this price level, gasoline prices would still face some upward pressure, requiring a degree of adjustment and potentially adding up to 0.15 percentage points to the IPCA if Petrobras implements a partial price increase. Therefore, fiscal balance alone does not guarantee that current fuel prices can be maintained,” noted Basiliki Litvac and Rodolfo Margato, the study’s authors.

In its baseline scenario, however, the firm expects oil prices to average $75 a barrel in 2027, which would allow the government to phase out these policies. “Since subsidies have been mitigating the increase in prices, their removal would be gradual,” Litvac argued.

She and Margato stressed that crude oil prices are not the only factor that needs to be considered at this point. Another is the so-called crack spread, or the difference between the price of the commodity and the market value of refined products such as gasoline and diesel. This indicator—a proxy for refinery profit margins—remains well above the levels seen over the past five years.

In simulations using different oil prices and crack spreads, the economists found that, at current levels ($115 a barrel), removing the tax exemption on gasoline could have an upside impact of between 0.05 and 0.74 percentage points on the IPCA, depending on prevailing refining margins. If oil prices return to $85 a barrel, the increase would range from zero to 0.22 percentage points.

A return to $75 a barrel, therefore, would allow the government to reverse subsidies and tax breaks while narrowing the gap between domestic and international prices without passing the increase on to consumers. “However, we recognize that risks remain to this more favorable oil price trajectory, creating an upside bias in our inflation forecast,” they wrote in the XP study.

As for U.S. monetary policy, the risk is that higher interest rates in the United States will strengthen the dollar and lead to exchange-rate pass-through in Brazil. “I no longer see the kind of dollar weakness that did so much to help domestic inflation,” said Solange Srour, UBS GWM’s head of Brazil macroeconomics. “The U.S. economy is holding up well, and unemployment remains low. The market believes the Fed will raise interest rates in December, and the latest inflation figures came in higher than expected. So the risk here is a weaker exchange rate.” In her view, “even if some fiscal adjustment is announced, the expected benefit of a stronger currency resulting from a change in the administration will not materialize.”

In XP’s exchange-rate model, the three most important factors are Federal Reserve policy, fiscal risks, and commodity prices. On the latter, Margato noted that price movements have been supportive of the real. The Brazilian currency had the third-best performance among emerging-market currencies through the second round of Brazil’s election and, even after depreciating by approximately 7% following President Luiz Inácio Lula da Silva’s victory, has continued to track the group average.

“The fact is that Brazil is a commodity exporter, and our terms of trade have improved significantly. The balance of payments is an important underlying strength. Estimates for both the trade surplus and foreign direct investment in Brazil have been revised upward. This is an important source of support for the exchange rate, even during periods of heightened domestic risk,” he noted.

Regarding the other two factors, the economist acknowledges the possibility of greater pressure in the opposite direction. “Interest rates appear to pose the greater risk. At the short end of the curve, rates respond to the possibility that the Fed may need to tighten policy further because economic activity remains strong and inflation persistently above 2%. The belly and long end of the curve, meanwhile, reflect growing concerns about fiscal risk, which is also something we will be discussing extensively in Brazil over the next few years.”

XP estimates that the average exchange rate in 2027 will be around R$5.30 to the dollar. However, in a simulation of a more severe stress scenario for the U.S. dollar, the exchange rate in Brazil could reach R$5.65. In that case, exchange-rate pass-through would add 0.45 percentage points to the IPCA over 12 months.

Barros, of Daycoval, noted that the wide spread between Brazil and the United States supports the exchange rate, even after adjusting for risk. “An exercise we conducted shows that only when this risk-adjusted spread falls below 3.9% do interest-rate changes amplify the exchange rate’s response. And given the rate cuts priced in for Brazil and the hikes expected in the U.S., we still have some room to absorb those moves. That threshold will only be crossed at the end of 2027,” he said.

He noted that the greater risk lies in the Fed accelerating its rate hikes. In Brazil, although the possibility of faster rate cuts cannot be ruled out, the expectation is that the Central Bank will maintain its pace of 0.25 percentage points per meeting. “From an economic activity standpoint, a slowdown is underway, but we have assigned less weight to the risk of a recession because of some fiscal stimulus measures recently approved. On the inflation side, there are supply-side shock challenges that could push prices higher,” he said.

*By Marcelo Osakabe — São Paulo

Source: Valor International

https://valorinternational.globo.com/
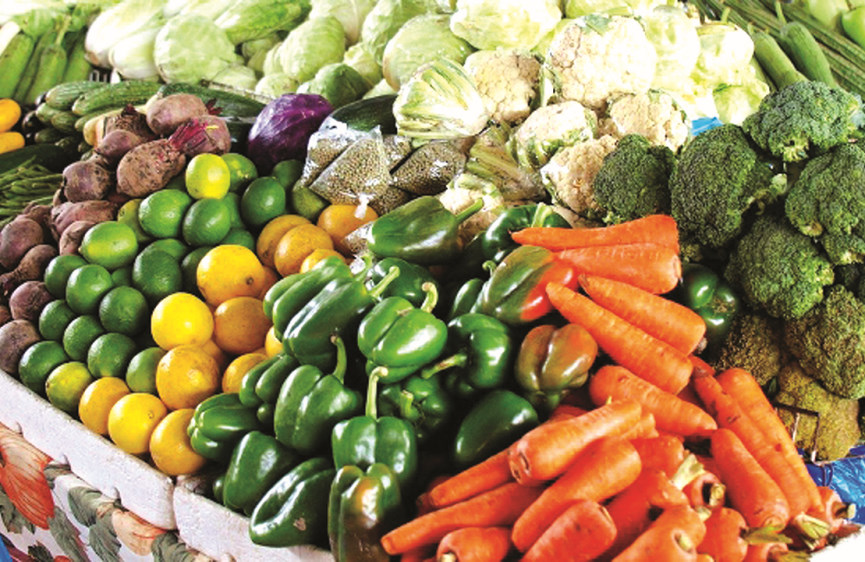


China is stepping up controls on pesticide and veterinary drug residues in imported agricultural products. Amid repeated notifications and shipment rejections involving suppliers from around the world, Brazil’s agricultural attaché in Beijing sent an alert to the country’s Agriculture Ministry this month, calling for stricter monitoring before shipments leave the country. The aim is to reduce risks to exports to China, Brazil’s largest customer in several segments, including soybeans and beef.

“In this environment, a single detection of a prohibited substance or a residue exceeding China’s MRL [maximum residue limit] can result in the return or destruction of a shipment and the suspension of export authorization,” says the document signed by agricultural attaché Leandro Diamantino Feijó, which Valor has seen.

He recommends removing inputs prohibited in China from Brazil’s production chain. According to industry sources, however, this possibility has been ruled out for now. One person familiar with the matter said the attaché’s warning was not intended to cause alarm but to improve monitoring.

The information is contained in a document dated October that refers to updates issued in August by China’s Ministry of Agriculture and Rural Affairs to its lists of prohibited and discontinued veterinary drugs and prohibited and restricted-use pesticides.

According to two sources, agricultural industry representatives have already discussed the matter with Brazil’s Agriculture Ministry.

One measure suggested by the attaché is to share the information with the ministry departments responsible for sanitary controls and with exporters’ associations. He proposes “removing substances prohibited in China from the supply chain and complying with veterinary drug dosage requirements and withdrawal periods to meet Chinese MRLs.”

He also recommends that exporters of plant-based products check maximum residue limits and the prohibitions and restrictions listed by China, taking into account potential differences between inputs approved for use in Brazil and those banned by the Asian country.

According to Feijó, China’s tougher enforcement measures have led to an increase in food import rejections by the General Administration of Customs of China (GACC) due to residue levels, affecting Brazil and other suppliers.

“There were no detections between 2020 and 2023. There were 22 shipments in 2024, concentrated in four declarations from three facilities, 13 in 2025 and five in the first half of 2026, almost all involving animal products. About two-thirds of the detections resulted from residues exceeding MRLs for substances approved for use, particularly fluazuron in beef (24 shipments),” the attaché says, referring to the rejection of Brazilian cargoes.

GACC data show that Brazilian beef exporters received 320 notifications from China for various types of noncompliance in shipments between January and August 2026, including issues involving residues, temperature, and labeling. The figure compares with 167 notifications in the same period a year earlier. According to the data, 82 violations recorded during the period in 2026 occurred in Mato Grosso state.

Luciano Vacari, CEO of NeoAgro Consultoria, says fluazuron has become a widely used veterinary product in Brazil’s cattle industry, recognized for its effectiveness in parasite control and for meeting the safety, sanitary, and efficiency requirements demanded in global markets. “However, something has changed. Recurring reports from China about fluazuron residues in Brazilian beef exports have set off alarm bells across the industry,” the expert says.

In his view, the problem stems from Brazil’s failure to effectively implement an individual animal traceability system. “Without such a system, it is impossible to accurately identify the animal from which the residue originated,” Vacari says.

The issue extends beyond the meat industry. In November 2025, China canceled the import of a 69,000-tonne shipment of Brazilian soybeans and suspended purchases from five facilities operated by four different companies following an alleged contamination involving 10 tonnes of wheat treated with pesticides. Brazil is not authorized to export wheat to China, and the pesticides used are banned in the Asian country.

Contacted by Valor, Brazil’s Agriculture Ministry and the country’s agricultural attaché in China did not respond to requests for comment. The Chinese Embassy in Brazil also did not respond. The National Union of the Animal Health Products Industry (Sindan) declined to comment. The Brazilian Association of Meat Exporting Industries (Abiec) said it would not comment because it had not been officially informed of the matter.

(Rafael Walendorff contributed reporting from Brasília.)

*By Nayara Figueiredo, Globo Rural — São Paulo

Source: Valor International

https://valorinternational.globo.com/
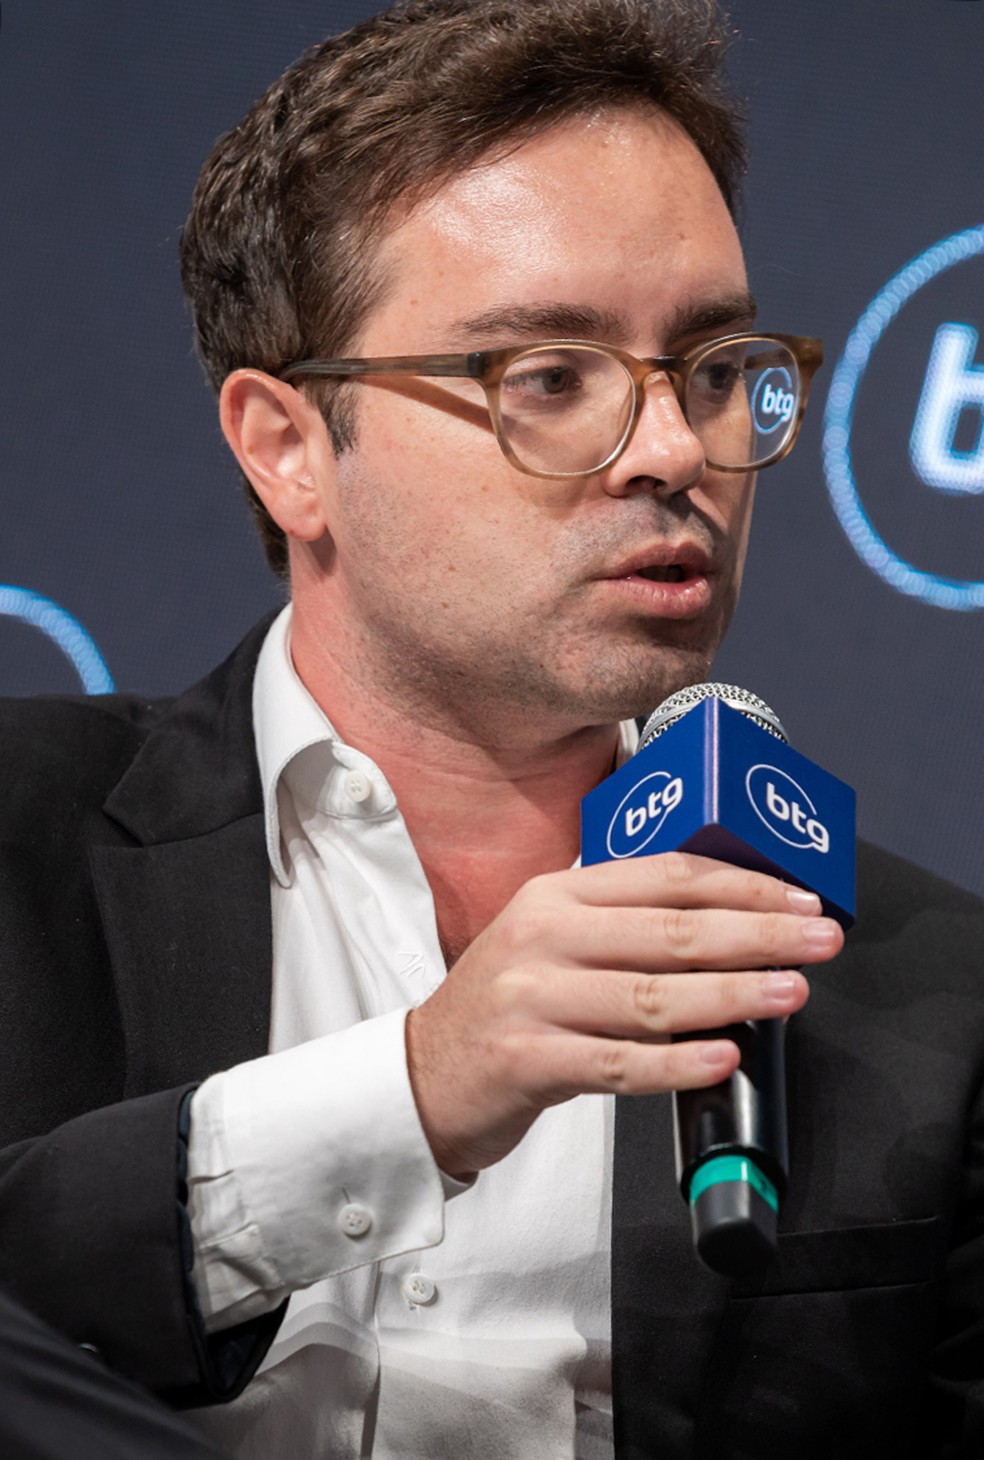


Luiz Guanais — Foto: Divulgação
Luiz Guanais — Photo: Divulgação

Large pharmacy chains are expanding vaccination and pharmacist consultation rooms to build customer loyalty and differentiate their physical stores as medication sales grow through apps and e-commerce platforms. Although health services still account for a small share of revenue, companies report they are linked to more frequent purchases and higher customer spending.

Luiz Guanais, a retail and consumer analyst at BTG Pactual, believes the services help chains attract customers. “Any way of differentiating your physical store ultimately helps attract more consumers,” he said. Vinícius Strano, executive director and head of research at UBS Banco do Brasil, noted that their main contribution is not direct revenue generation. “It is more of a mechanism for keeping customers in the store and building loyalty.”

Members of the Brazilian Association of Pharmacies and Drugstores (Abrafarma), which represents large industry chains, operate 9,248 rooms offering pharmacist services. According to association CEO Sérgio Mena Barreto, the challenge now is to make better use of the infrastructure already in place. “The physical investment has been made, and it does not appear to be the main constraint today,” he said. “The challenge now is primarily to increase the productivity and use of this infrastructure.”

Valor interviewed the four pharmacy chains listed on Brazil’s B3 exchange—RD Saúde, which owns the Raia and Drogasil brands, Pague Menos, Panvel, and d1000. The companies identified increasing the use of existing rooms and integrating them with digital channels as priorities.

RD Saúde expects to make progress “by expanding the services offered, increasing the use of existing rooms, and integrating physical and digital channels,” said Juliana Cervan, the company’s health services director. At Panvel, “the focus is on increasing the productivity of existing infrastructure,” according to Adriana Vasco, executive manager of new businesses.

The strategy comes as digital channels account for a growing share of sales. In the second quarter, they generated 33.7% of Panvel’s retail revenue, 31% of RD Saúde’s sales, and 24.1% of Pague Menos’s revenue, according to the companies’ financial reports.

Mena Barreto believes e-commerce expansion reinforces the importance of in-person services. “The more transactional the purchase of medication becomes, the less a physical store needs to serve merely as a place for transactions and the more it can become a space for care.”

Marcelo Cardoso, vice president of d1000, also sees the channels as complementary. “Digital channels meet growing demand for convenience and speed. Health services, meanwhile, depend on proximity, trust, and human interaction.”

Pague Menos illustrates this integration through sales of GLP-1 analog medications. This class includes injectable pens used to treat diabetes and obesity. About 60% of these products are sold through digital channels, according to the company’s financial report. The chain offers free medication administration and body assessments to customers who buy the pens. “Customers purchase through the app or website and, when they collect the product, find a health care structure that can meet other needs,” said Marcel Desco, the company’s vice president of customers and marketing. Store pickup accounted for 49% of the chain’s digital orders in the second quarter.

The services still account for a small share of revenue. In the second quarter, they represented 0.2% of RD Saúde’s sales, 0.4% of Pague Menos’s revenue, and 1.4% of Panvel’s retail revenue. The companies argue that returns come from purchase frequency and customer spending.

Panvel Clinic users make purchases more than 3.5 times as often as other customers and spend four times as much annually, Vasco noted. At Pague Menos, customers who use pharmacist consultation rooms buy about 2.4 times as frequently and spend 3.3 times as much as standard customers. The company stressed that the data shows an association between service use and a more recurring relationship. At d1000, users spend 10% more and shop 15% more frequently. RD Saúde monitors these indicators but does not disclose the figures.

Mena Barreto argues that the economic value of the services must account for their effect on customer relationships, not only direct revenue. “Sometimes a service loses money and is not profitable, but at the same time it builds patient loyalty,” he said. “Those effects cannot be calculated separately.” Guanais of BTG Pactual added that the extra revenue can also help cover fixed costs, such as rent and employees, in a low-margin business.

Vaccination is the fastest-growing service. According to Abrafarma, Clinicarx, a platform member chains use to record and monitor pharmacist services, registered a 74% increase in doses administered in the first half of the year. RD Saúde administered 470,000 vaccines during the period. At Panvel, vaccinations account for 80.3% of service revenue and grew 15.1% in the second quarter.

The chains’ next step is to turn one-time visits into continuous monitoring, particularly for patients with chronic illnesses. Panvel cited cardiovascular and metabolic conditions, including diabetes and obesity, as “important opportunities.” Pague Menos listed blood glucose, glycated hemoglobin, and lipid profile tests among its priorities.

The expansion of consultation rooms is also accompanying new store openings. According to Vasco, virtually every new Panvel location now opens with at least one service room as part of the chain’s plan to reach 1,000 stores by 2030. D1000 plans to increase the number of stores offering pharmacist services from 138 to 160 in 2027, Cardoso said. RD Saúde and Pague Menos do not disclose specific targets or investments.

Guanais believes growing e-commerce competition will be one of the variables investors “closely scrutinize” over the coming quarters. Mena Barreto identified another challenge for the chains: increasing consumer awareness of the services available in stores. “A significant share of the population still does not know everything they can do inside a pharmacy.”

*By Vitória Nascimento — São Paulo

Source: Valor International

https://valorinternational.globo.com/