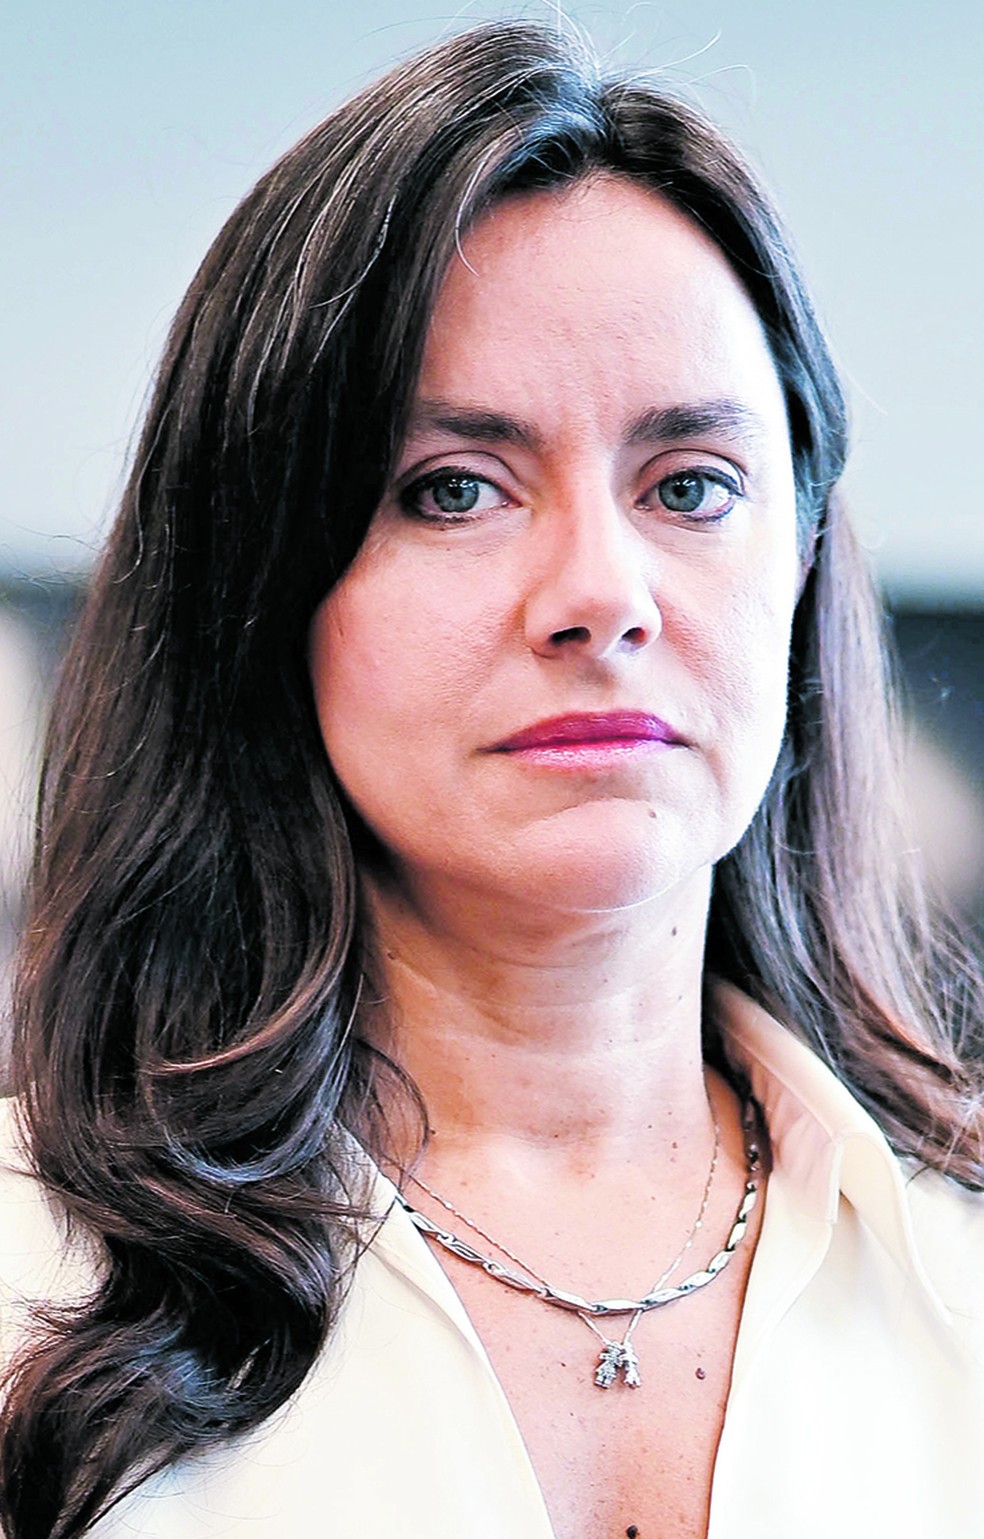
Rafaela Vitória — Foto: Washington Alves/Valor
Rafaela Vitória — Photo: Washington Alves/Valor

Bringing Brazil’s public finances under control will require slowing the growth of mandatory spending, but economists interviewed by Valor say that does not mean dismantling the social safety net guaranteed by the Constitution. Rather, fiscal consolidation is essential to preserving social programs over the long term and ensuring the government has resources to respond to emergencies.

This is the first article in “False Dilemma”, a series exploring how Brazil can reconcile fiscal responsibility with efforts to reduce inequality. The reports will examine the challenges of keeping social protection programs sustainable, tackling privileges and improving public-sector efficiency. Other articles will explore the economic costs of inequality, including its impact on productivity, as well as indicators of violence in Brazil, among other issues.

Unchecked public spending can fuel inflation, which hits low-income households hardest, said Rafaela Vitória, chief economist at Inter. “Inflation is not out of control today, but we are paying the price of high interest rates to keep it low. Households are burdened with debt because of this. Fiscal discipline matters because it helps improve the well-being of low-income people. It is an indirect form of social welfare.”

Bráulio Borges, a director at LCA and researcher at the Brazilian Economics Institute of the Getulio Vargas Foundation (FGV Ibre), warned that prolonged fiscal instability could ultimately force the government to print money to service its debt.

“That results in too much money circulating in the economy, the currency depreciates and inflation rises. And the inflation tax is regressive.”

The proposals for curbing spending growth bear little resemblance to the sweeping cuts to primary expenditure imposed by Argentine President Javier Milei in 2024. Instead, economists point to changes in Brazil’s minimum wage policy as one of the most important steps toward fiscal consolidation. Their proposals would preserve purchasing power while allowing annual increases of between 0.5% and 1.5% above inflation.

Some argue that the best approach would be to sever the link between the minimum wage and pension and social assistance benefits. Other recommendations include ending the automatic link between health and education spending and government revenue, imposing an effective ceiling on total expenditure, eliminating fraud and reducing overlap among social programs.

Although the economists differ on how these changes should be implemented, they agree that fiscal responsibility and social protection are not mutually exclusive.

Borges pointed to President Luiz Inácio Lula da Silva’s first administration as evidence. “When he took office in 2003, he raised the primary surplus target from 3.75% to 4.25% and created [cash-transfer program] Bolsa Família. That shows there is no incompatibility between fiscal and social policies.”

Marcos Lisboa, former president of Insper and economic policy secretary during Lula’s first term, said constitutional and legal restrictions make substantial cuts to major spending categories difficult. Wages and pensions cannot be reduced, while pension, health and education spending are subject to their own adjustment formulas and revenue-linked requirements.

Slowing expenditure growth is therefore the more viable option, although Lisboa also favors removing those automatic links.

Carlos Kawall, founding partner of Oriz, noted that no presidential candidate had advocated a draconian fiscal policy involving an immediate reduction in benefits equivalent to 2% or 3% of GDP.

“What is being proposed is a policy to contain the growth of social spending, keeping that expenditure from rising as a share of GDP, and changing indexation rules so that, within five years, we can put public debt on a path toward stabilization. That signal would bring interest rates down and prevent the crisis we could face if we stick to the cosmetic measures suggested so far.”

Debt pressures

Economists warn that Brazil’s current debt burden and the pace at which it is growing are unsustainable.

Central Bank data show that gross general government debt reached 82.93% of GDP in September, up 5.09 percentage points from a year earlier. In December 2022, the ratio stood at 71.68%.

The 12-month nominal deficit reached 9.5% of GDP in September, compared with 4.6% in December 2022, reflecting the burden of high interest rates. At its most recent meeting, the Central Bank’s Monetary Policy Committee (Copom) held the benchmark Selic rate at 13.75%, interrupting its previous easing cycle.

Samuel Pessôa, an economist at BTG Pactual and researcher at FGV Ibre, said an economy operating with a real benchmark interest rate of 8% a year cannot be considered healthy.

“The Brazilian economy is sick. Unless we bring interest rates down, we will enter a crisis. No economy can withstand interest rates this high for very long. And if we force the Central Bank to cut rates, inflation will return. We have done that before.”

Economists say stabilizing public finances will require slower spending growth, including on pensions and social assistance, given their weight in the federal budget.

A report by the Independent Fiscal Institution (IFI) shows that pension benefits totaled R$1.03 trillion in 2025, while spending on the Continuous Cash Benefit (BPC), a social assistance program, reached R$127.2 billion.

Together, the two programs accounted for 9.1% of GDP and 48.2% of central government primary expenditure. The proposed 2027 budget projects combined spending of 9.2% of GDP.

“The debate is not about whether social protection should be maintained. It is about how quickly that protection should improve. I support a 0.5% annual real increase in the minimum wage. That was the average growth rate of labor productivity over the past 40 years,” Pessôa said.

Productivity, he explained, determines the pace at which resources expand in the economy. “Some advocate a 2% real increase, but that is incompatible with what the economy can deliver.”

Since 1995, the minimum wage has risen 195% in real terms, while labor productivity has increased just 22%, he said.

Minimum wage reform

Under current rules, real increases in the minimum wage automatically raise the floor for pensions and social assistance benefits such as the BPC. As a result, pay increases for active workers also drive up a substantial portion of federal spending.

Fernando Veloso, research director at the Institute for Social Mobility and Development (IMDS), said this arrangement has no parallel in other countries, where pension adjustments generally aim only to preserve purchasing power.

Brazil’s current formula adjusts the minimum wage for inflation plus GDP growth, subject to a cap of 2% on real gains. Veloso argues that linking benefits to the minimum wage makes wage increases more expensive for the government and complicates spending control.

He proposes adjusting the minimum wage for inflation, as measured by the IPCA consumer price index, with real gains tied exclusively to labor productivity. Pensions, meanwhile, would receive inflation adjustments plus a real increase that would not necessarily match the minimum wage.

Gabriel Leal de Barros, chief economist at ARX, also supports real minimum wage increases of 0.5% a year, reflecting productivity growth. But he believes the best solution is to eliminate the link between the minimum wage and pension and social assistance spending, even if doing so requires the government to invest political capital in a constitutional amendment.

“We need to cut that umbilical cord. It is worth the effort because the impact on market expectations would be enormous. It would radically change the trajectory of public finances, affecting the yield curve and the Treasury’s borrowing costs.”

The goal, Barros emphasized, is to preserve the purchasing power of pension and social assistance benefits, “without any loss in real terms.”

Fabio Giambiagi, also a researcher at FGV Ibre, proposes creating a separate national wage floor for the labor market. Initially set at the same level as the minimum wage, it would subsequently increase at a faster pace, without automatically passing the full adjustment on to minimum pension benefits.

The arrangement would allow wages for active workers to continue rising in real terms while limiting the impact on pension spending.

“This is not a squeeze on retirees. A squeeze means a reduction,” Giambiagi said. “The minimum wage and the pension floor would continue to rise, but the increase would be larger in the labor market.”

Giambiagi also advocates freezing spending growth in real terms in 2027, the first year of Lula’s fourth term, followed by a rule limiting annual increases to inflation plus 1.5%.

He stressed that the proposal is fundamentally different from an abrupt spending-cutting program.

“Milei reduced Argentina’s primary spending by 27% in real terms in 2024. In Brazil, that would not only be unworkable but an aberration,” he said.

For Giambiagi, a commitment to zero real spending growth in the first year would provide an opportunity to put public finances in order and signal a change in fiscal direction, without triggering a contraction comparable to Argentina’s.

Budget rigidity

Beyond minimum wage reform, economists broadly agree that Brazil’s current fiscal framework has lost coherence because its overall spending ceiling coexists with expenditure commitments linked to revenue growth, particularly in health and education.

As a result, measures designed to boost tax revenue also increase some mandatory expenses, which account for more than 90% of spending in an already highly rigid budget.

The government has also introduced mechanisms allowing certain expenditures to be excluded from the fiscal rules, further weakening the framework’s ability to restrain total spending.

For health care, Giambiagi proposes aligning the minimum spending requirement with the overall expenditure ceiling. In other words, mandatory health spending would follow the same adjustment formula as the fiscal framework.

The government could still allocate additional resources to the sector, but those funds would have to compete with other budget priorities.

In education, Giambiagi recommends adjusting federal contributions to the Fund for the Maintenance and Development of Basic Education (Fundeb) by inflation alone.

His argument is that Brazil’s school-age population is shrinking because of demographic changes, making it possible to increase spending per student in real terms even if total funding remains constant after inflation.

Barros said reforms to health and education spending must involve not only the federal government but also states and municipalities.

Borges noted that congressional earmarks and spending through the Federal District Constitutional Fund (FCDF) are also linked to revenue and should be reviewed.

Together, changes to those spending links and the minimum wage policy would account for “70% of the spending-reduction package,” he said.

Borges considers limiting annual real minimum wage increases to between 1% and 1.5% “feasible.”
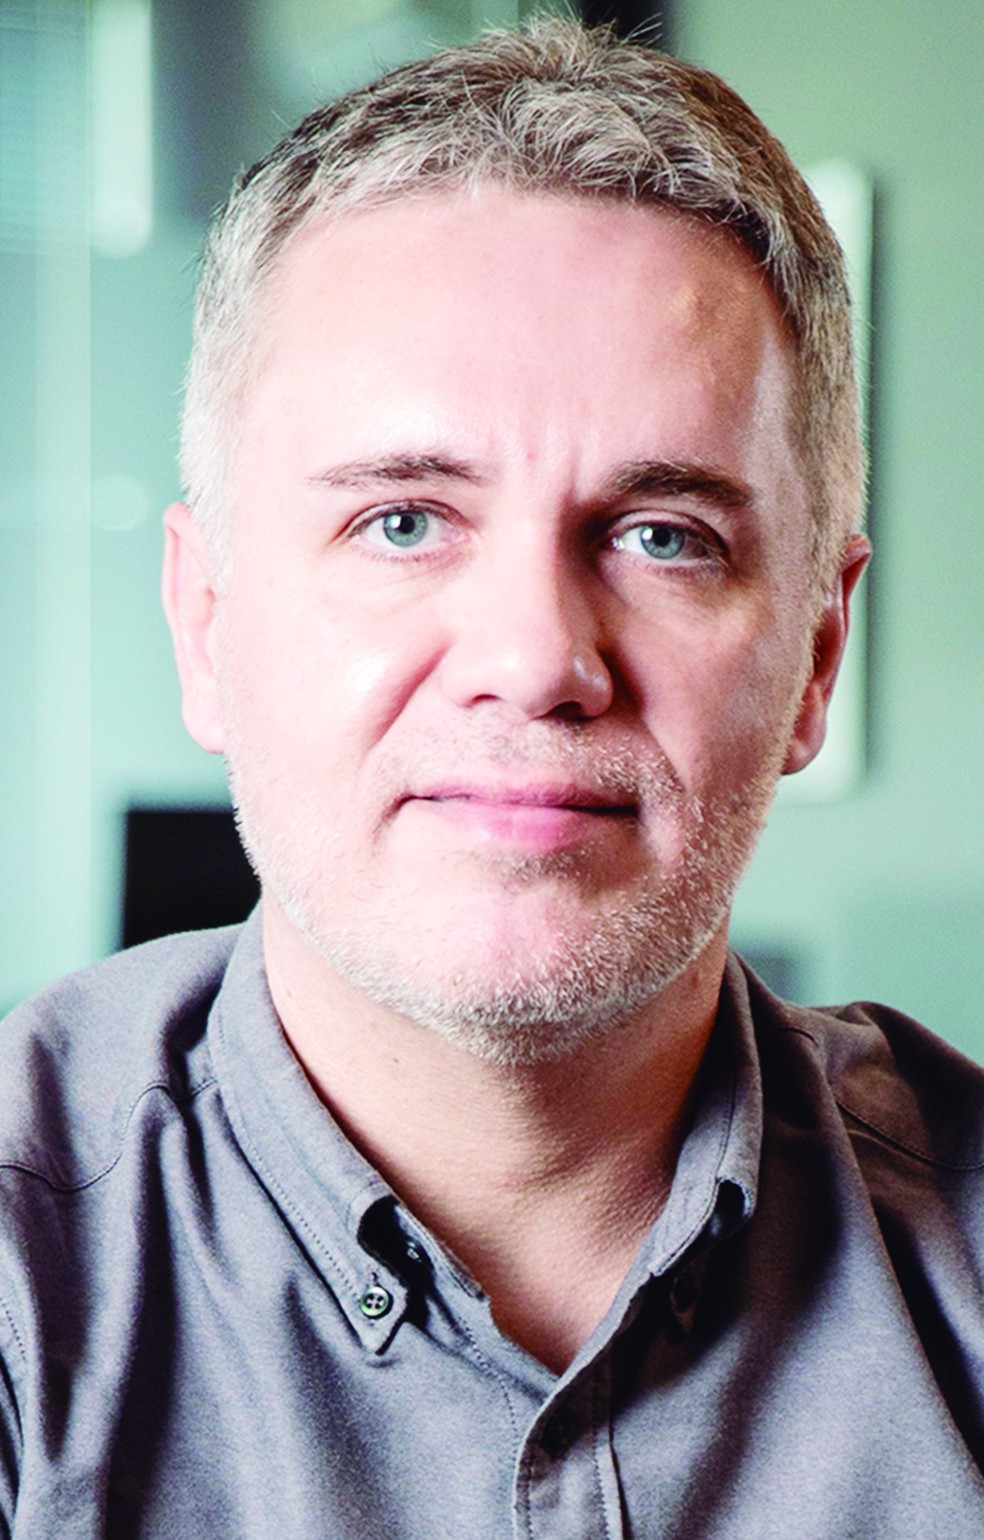
Braulio Borges — Foto: Anna Carolina Negri/Valor
Braulio Borges — Photo: Anna Carolina Negri/Valor

Social program efficiency

Alongside efforts to restrain expenditure growth, economists advocate improving the design and targeting of social programs.

Veloso argues that their success should be measured by how effectively they reduce poverty, rather than by the amount of money spent.

He described Bolsa Família as an internationally recognized anti-poverty program that delivers results at a relatively low cost. But he believes its targeting has deteriorated since the pandemic.

One of his main criticisms concerns the introduction of a minimum benefit per family, dating back to the R$600 payments under “Auxílio Brasil” during the pandemic.

Combined with an increase in single-person households receiving benefits, the policy has reduced the extent to which payments vary according to family income and household composition.

Barros also sees a need to redesign social programs to eliminate overlapping benefits and combat fraud.

He estimates that each of these measures could potentially save between R$25 billion and R$30 billion a year.

Revenue measures

Pessôa cited several possibilities, including taxing currently exempt securities, reducing tax expenditures such as personal income tax deductions for health and education, and taxing dividends distributed by companies operating under special tax regimes, including Simples and the presumed-profit system.

While economists agree that fiscal consolidation must focus primarily on slowing spending growth, they acknowledge that revenue measures could also help.

Although the additional revenue would offset the higher spending and prevent the fiscal deficit from worsening, it would do little to contain aggregate demand.

He cautioned, however, that raising taxes to finance a 2% real increase in the minimum wage would not be the best approach.

That is because minimum wage recipients tend to spend virtually all their additional income, sustaining pressure on the economy.

Inflation and interest rates would therefore remain elevated.

*By Marta Watanabe and  Vinícius Lucena — São Paulo

Source: Valor International

https://valorinternational.globo.com/


In Brazil, tax breaks have historically been granted to cars purchased by people with disabilities, professional drivers such as taxi operators, and other groups—the latter category often linked to programs negotiated between the government and automakers. This time, the provisional presidential decree No. 1,399/2026, published on Wednesday (4) and addressing the excise (or the Selective Tax), includes vehicles with a sustainable-version certification issued by the Ministry of Development, Industry, Trade and Services (MDIC).

The sustainable-version certification is tied to the Sustainable Car program, launched in July 2025. The initiative, which exempted a list of models from the Industrialized Products Tax (IPI), was created with an environmental goal in mind. It granted tax exemptions to cars with low pollutant emissions and a high proportion of recyclable materials. In practice, however, it was designed to boost sales at a time when the market was sluggish.

lthough electric cars also produce low emissions, they were excluded because the program was limited to vehicles manufactured in Brazil. No electric cars were being produced in the country at the time, and under the program’s criteria, even models that are now imported in semi-knockdown (SKD) form for final finishing in Brazil remain ineligible. In other words, all Chinese models were excluded. The measure prompted complaints at the time from EV brand representatives.

The program initially covered a limited number of models—mostly smaller, lower-priced cars. Following lobbying efforts by automakers in Brasília, the list was subsequently expanded to include additional configurations and models launched after the program was created.

The list of eligible vehicles now includes 14 versions of the Chevrolet Onix, Fiat Mobi, Fiat Argo, Citroën C3, Hyundai HB20, Renault Kwid, Volkswagen Polo, and Volkswagen Tera. With the IPI exemption, these models—whose entry-level versions are priced at around R$70,000, although higher-end trims can cost considerably more—received discounts ranging from R$3,000 to as much as R$13,000.

The addition of new models was even announced by Geraldo Alckmin, the vice president and then head of the MDIC, on his Facebook account. Alckmin is one of the program’s strongest supporters. After its launch, he began visiting car dealerships on Saturdays to monitor sales performance.

The program did, in fact, attract consumers. According to the National Association of Vehicle Manufacturers (Anfavea), sales of eligible models rose 28.9% from January to September. Over the same period, the market for passenger cars and light commercial vehicles grew 16.6%.

The market expansion prompted Anfavea to revise its full-year projections. In 2026, sales of new vehicles are expected to exceed 3 million units for the first time in 14 years.

Car rental companies benefited from the program as well, and to a greater extent than end consumers. Anfavea data show that of the 374,000 eligible vehicles sold from January to September, 277,000 were sold through direct sales and 97,000 through retail channels.

Over the years, the automotive industry’s tax system has been shaped by rules tailored to specific types of vehicles. These rules have also almost invariably been followed by expansions of the lists of eligible products. In some cases, automakers have even adapted product development and launch plans to ensure their vehicles qualify.

The best-known example was the economy car program. It was launched in 1993 after then-President Itamar Franco asked Volkswagen executives to bring back the Beetle. In return, he would grant the model an IPI exemption.

Volkswagen promptly agreed to the president’s request. Itamar Franco, an honored guest at the relaunch celebration, rode in a convertible Beetle, echoing Juscelino Kubitschek’s appearance at the inauguration of Volkswagen’s factory in São Bernardo do Campo in 1959.

What followed, however, was an intense, prolonged lobbying effort by all automakers to have their own models included in the tax benefit. Legislation was then introduced for economy cars, exempting not only the Beetle but also vehicles equipped with 1.0-liter engines from the IPI.

In the next phase, automakers adapted their new models to fit the category, eventually expanding the list of IPI-exempt vehicles far beyond the original idea of a bare-bones, no-frills car. The industry then came up with the 1.0-liter turbo engine, demonstrating that when tax breaks are at stake, automakers can learn—and do—just about anything.

Brazil’s car tax breaks reflect decades of automakers’ influence on policy — Foto: Pixabay
Brazil’s car tax breaks reflect decades of automakers’ influence on policy — Photo: Pixabay

*By Marli Olmos, Valor — São Paulo
Source: Valor International
https://valorinternational.globo.com/


The National Confederation of Industry (CNI) criticized the 11.3% rate set for the Contribution on Goods and Services (CBS), which is scheduled to take effect in January 2027, saying it is higher than necessary to maintain the current rate. The organization argued that the Senate should discuss lowering it to prevent additional costs for businesses.

The Federal Court of Accounts (TCU) announced that the benchmark rate for the tax would be 11.3%. The CNI acknowledged the unprecedented assistance provided by the court in setting the rate, but believes the figure is higher than necessary to maintain the tax rate

“Further discussion is needed to determine the final rate, which will be set by the Senate by December 15,” the CNI said in a statement.

In the confederation’s view, the Senate’s review must “weigh political and technical considerations,” drawing on TCU’s study, and “strike a balance between the expectations of consumers and those of productive sectors.”

The confederation said the tax rate already is above the threshold appropriate for a developing country and warned against the “shortsighted view that there are no limits to imposing new costs on consumers.”

If senators do not approve the rate by December 15, the figure set by the TCU will take effect.

The tax reform replaces the Social Integration Program (PIS), the Contribution for the Financing of Social Security (Cofins), the Tax on the Circulation of Goods and Services (ICMS) and the Tax on Services (ISS). It also reduces the rate of the Tax on Industrialized Products (IPI) to zero for most products. The reform creates the CBS and the Tax on Goods and Services (IBS) to replace these levies.

According to CNI, TCU’s projection was based on the average tax rate from 2012 to 2021. However, PIS-Cofins revenue was boosted because ICMS and ISS were included in its calculation base. As a result, the tax rate calculated by the court is higher than what would have been reached, according to the CNI, had a more recent reference period been used.

“From a technical standpoint, the need for further discussions is justified by the nature of projection exercises, which are subject to variables involving a range of uncertainties,” the CNI said.

In the confederation’s view, discrepancies in the projections may stem from variables such as the reduction in tax evasion expected from the reform, the discount applied to public-sector purchases, and assumptions about revenue from the Selective Tax and the residual IPI.

CNI said current tax rate already is above the threshold appropriate for a developing country  — Foto: Pixabay
CNI said current tax rate already is above the threshold appropriate for a developing country — Photo: Pixabay

*By Hamilton Ferrari— Brasília
Source: Valor International
https://valorinternational.globo.com/


Finance Minister Dario Durigan says no concrete measures have been discussed so far — Foto: Reprodução/GloboNews

Finance Minister Dario Durigan says no concrete measures have been discussed so far — Photo: Reprodução/GloboNews

President Luiz Inácio Lula da Silva said Thursday (5) that fiscal and legal responsibility are necessary to attract foreign investment to Brazil. Amid growing market concerns over fiscal policy, he made the remarks just hours after meeting with Vice President Geraldo Alckmin, ministers, former ministers, and economists close to him.

“We must have legal responsibility and fiscal responsibility. That is why we cannot treat partnerships as a game,” he said during the first meeting of the National Council for the Industrialization of Critical and Strategic Minerals (Cimce), at the Planalto Palace. “We know that, to attract investment, we need to have our economy in order. People want to know whether we are serious.”

Earlier in the day, at the Alvorada Palace, Lula met with former Finance ministers Fernando Haddad and Guido Mantega; Alckmin; Finance Minister Dario Durigan; Planning and Budget Minister Bruno Moretti; Chief of Staff Miriam Belchior; Management and Public Service Innovation Minister Esther Dweck; Brazilian Development bank (BNDES) President Aloizio Mercadante; and former BNDES president Luciano Coutinho.

Also in attendance were economists Laura Carvalho, a professor at the University of São Paulo (USP) and an associate researcher at the Brazilian Institute of Economics of the Getulio Vargas Foundation (FGV Ibre), and Eduardo Moreira, founder of news portal ICL. The meeting participants are economists with heterodox views. Further meetings with civil society and different sectors of the market will be held, Durigan said.

“There was no discussion of specific measures, and this is not yet the time to address any specific measures,” the minister told reporters after the meeting, adding that participants agreed on their assessment of the economy and the paths to be followed in the coming years. He did not confirm, however, whether the federal government intends to submit proposals to the National Congress this year.

The gross general government debt (DBGG) reached 82.9% of GDP in recent months, more than 10 percentage points higher than at the start of Lula’s third term, and projections continue to point to further increases in the coming years. The central government’s 12-month cumulative primary deficit stands at R$49.5 billion, or 0.38% of gross domestic product (GDP).

Proposals under way


Despite the lack of concrete proposals at the meeting, it marked the first step toward defining measures that could be adopted. Until now, discussions with the president had focused on trying to convince him of the need to adjust public finances. But Lula has shown little urgency in moving forward with the issue, according to government sources who spoke to Valor.

The proposals are expected to be presented to the president after he returns from trips to Turkey and the Philippines next week, Durigan said. The finance minister and Moretti will be responsible for organizing suggestions based on the meeting’s discussions. According to government sources, both had already been working on assessing possible measures, discussing their effects individually and seeking to identify alternatives that Lula might accept.

The challenge is to find a middle ground that improves the trajectory of public finances without imposing losses on the population or undermining social programs, measures to which Lula has shown resistance. Economic officials, however, believe it is important to make progress on structural changes to public spending, particularly mandatory expenditures, which are on an upward trajectory and put pressure on the budget, making it harder to stabilize public debt.

Proposals discussed so far, such as using the midpoint of the fiscal target as the benchmark for budget freezes and allowing mandatory spending to be frozen, are considered important to give budget management some breathing room. Public finance experts, however, believe these measures must be accompanied by more far-reaching changes to send a consistent signal that public finances are sustainable. There is still no agreement on which measures Lula will be willing to accept.

Defining these measures also hinges on the president’s political priorities. Until now, Lula had been less focused on fiscal discussions and more concerned with responding to what he interpreted during the second round of the elections as a public desire for changes in the way the government operates, expressed above all in the streets and through mobilization on social media. Government sources say Lula’s political timetable differs from that of the economic team, requiring caution in presenting proposals.

In this context, ministers have adopted an approach described as almost “educational” to explain to the president why spending needs to be reviewed. Their argument is that public spending will have to be “rationalized” to ensure the sustainability and continuity of social programs. In their conversations, they have avoided even using the expression “fiscal adjustment.”

Among the spending “rationalization” measures under consideration is the possibility of creating greater coordination between the constitutionally mandated minimum spending levels for health and education, allowing states and municipalities to adjust some expenditures to their demographic needs.

On the revenue side, discussions continue over taxing securities such as Real Estate Credit Bills (LCIs) and Agribusiness Credit Bills (LCAs). One faction within the government argues that the tax should be levied through the income tax system, which would require debate in Congress, rather than through the Tax on Financial Transactions (IOF), on the grounds that the latter would be poorly received by financial markets.

Also under discussion is strengthening the agenda to combat special privileges, particularly excessive salaries in the judiciary, military pension benefits and congressional budget amendments. In his remarks after the meeting, Durigan said topics discussed included improving fiscal results, the quality of public spending, interest rates, international pressures on fuel prices and the cost of living for the population.

Asked about changing the parameters of the fiscal framework, the minister declined to disclose any decisions in advance. He said, however, that the government wants to move toward primary surpluses in the coming years by reinforcing the current fiscal rules. The primary balance targets in the Budget Guidelines Bill are surpluses of 0.5% of GDP in 2027, 1% in 2028, 1.25% in 2029 and 1.5% in 2030.

*By Giordanna Neves, Lu Aiko Otta, Mariana Andrade and Lucas Teixeira — Brasília

Source: Valor International

https://valorinternational.globo.com/
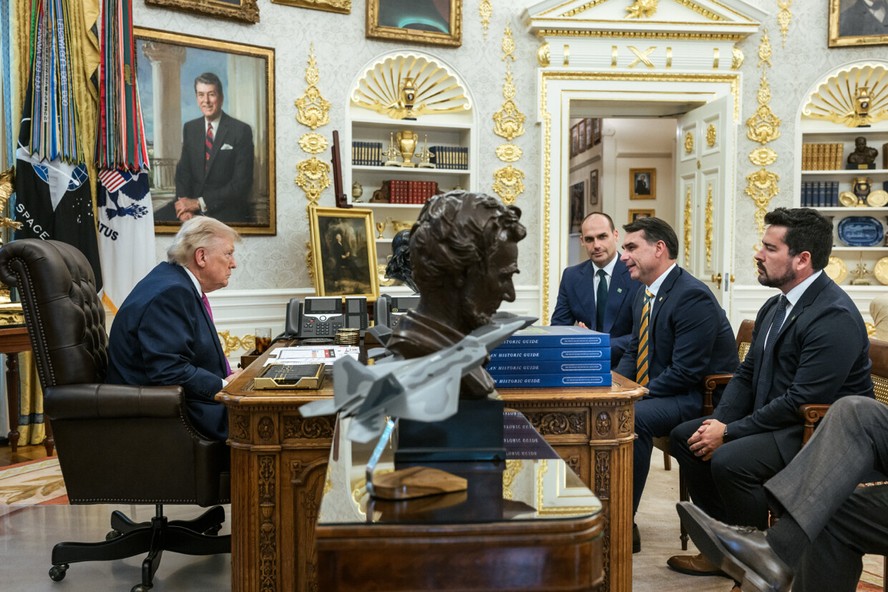


The defeat of U.S. President Donald Trump in the midterm elections is expected to have a negative impact on the Bolsonaro movement and could open the door for more moderate sectors of the right to vie for leadership of the political side. But the result alone is not expected to dislodge the group from its position as the main electoral force on Brazil’s right, experts interviewed by Valor said.

Senator and former presidential candidate Flávio Bolsonaro (Liberal Party, PL, Rio de Janeiro), former federal lawmaker Eduardo Bolsonaro, and other leaders of the group have not immediately commented on the outcome of the midterms.

Fernando Bizzarro, who holds a PhD in political science from Harvard University and is a professor at Boston College, believes the change in the composition of the U.S. Congress will have little impact on relations between the two countries. Congress can also influence decisions through budget approval. According to him, the president retains autonomy over foreign policy, including tariffs and bilateral relations.

For Bizzarro, the most significant effect of Trump’s defeat is symbolic. Following the Bolsonaro movement’s loss to Luiz Inácio Lula da Silva (Workers’ Party, PT), the U.S. result represents another setback for the populist right in the Americas, which had been gaining ground, the professor said. “It seems the tide is now turning,” he said.

Bizzarro cautions that this string of defeats does not necessarily mean a direct loss of electoral strength for the Bolsonaro movement. He points to Flávio’s performance and the presence of the Bolsonaro surname among lawmakers and governors elected in the elections. “Bolsonarism is still the main electoral movement within the Brazilian right,” he said.

The professor does not, however, rule out an opening for a non-Bolsonaro-aligned right in the next elections. Trump’s weakening could benefit moderate sectors without diminishing the Bolsonaro movement’s electoral strength. “Both things can be true,” Bizzarro said, summing up his view that the Bolsonaro movement remains strong but could face tougher competition within the right.

Bizzarro believes that openly associating with Trump is likely to become less electorally appealing in Brazil. According to him, U.S. support and the tariffs imposed on Brazil hurt Flávio’s voting intentions during the campaign, leading the senator to mention Trump less frequently in the runoff. Following the defeat, he expects the right to continue looking to the U.S. as a point of reference while avoiding public displays of closeness to the Republican.

Jorge Chaloub, a professor of political science at the Federal University of Rio de Janeiro (UFRJ) and the Federal University of Juiz de Fora (UFJF), and a researcher of right-wing movements, believes Trump’s defeat has a greater impact in Brazil because of the Bolsonaro movement’s alignment with the American radical right. “It seems to me that the impact is greater than usual,” he said.

Chaloub explains that the rapprochement has gone beyond a strategic relationship to include explicit support for Trumpism and initiatives to pressure Brazil. In his view, the ties affect the Bolsonaro family’s image. “The silence has to do with that,” he said, referring to the lack of statements from Flávio and Eduardo. He believes that acknowledging their ally’s setback could be interpreted by supporters as a sign of defeat for their political group.

The professor believes Flávio’s and Trump’s losses could lead members of the right to seek alternatives to the Bolsonaro movement. He stresses, however, that former president Jair Bolsonaro still commands the largest electoral capital within this political camp and was able to transfer votes to his son quickly.

Chaloub sees different calculations at play among lawmakers and presidential candidates. For lawmakers, maintaining close ties with the former president may be advantageous; for those running in a national election, the association could be an obstacle.

“It is difficult to win with Bolsonaro, given that he and his son lost the last elections, but it also seems even harder to be competitive without Bolsonaro,” he said.


In the political scientist’s view, the fact that important leaders remain outside the country or in prison could create an opening for the Bolsonaro movement to lose its dominance on the right. He does not expect an immediate break with Trump. The most likely scenario, he said, is that Bolsonaro supporters will keep a lower public profile and make “fewer overtures” to the U.S. president.

Paulo Figueiredo, an influencer and ally of the Bolsonaro family in the U.S., was one of the few members of the group to comment on the elections. He celebrated the result in Florida, where he and the Bolsonaros live. “Thank God, my free state of Florida remains Republican […] At least that,” he wrote on social media.

The grandson of former president João Figueiredo, the last leader of Brazil’s military dictatorship, Paulo has lived in the U.S. since 2016. He was charged by the Office of the Prosecutor General (PGR) over alleged involvement in the coup plot and suspected obstruction of justice, for allegedly working in the U.S. to pressure Brazilian authorities. The cases have not yet resulted in a conviction by the Supreme Court.

Flávio is in the U.S., where he fled after the presidential defeat and amid Federal Police (PF) investigations into potential corruption and money laundering. Before the trip, Justice Alexandre de Moraes had ordered him to surrender his passports to the Federal Police within 24 hours, after the agency cited a risk of flight. Eduardo, meanwhile, has lived in the U.S. since 2025. He was sentenced by the Supreme Court to four years and two months in prison for obstruction of justice, after pressuring the Court through U.S. sanctions last year.

*By Guilherme Carvalho — São Paulo

Source: Valor International

https://valorinternational.globo.com/


Fabiano Zavanella — Foto: Ana Paula Paiva/Valor
Fabiano Zavanella — Photo: Ana Paula Paiva/Valor

Labor law firms across Brazil have seen a surge in consultations since a constitutional amendment ending the six-day workweek was enacted on October 16. With the requirement to provide two paid days off per week taking effect on December 16, employers are seeking legal advice on whether proposed changes to working arrangements could expose them to lawsuits from employees or unions. Lawyers warn that a wave of litigation is likely.

Constitutional Amendment No. 141 was approved between the first and second rounds of the presidential election, fulfilling one of President Luiz Inácio Lula da Silva’s campaign pledges. Some business leaders, however, had hoped the measure would be repealed or suspended if Senator Flávio Bolsonaro of the Liberal Party (PL) won the election, after he received more votes than President Lula in the first round.

Amid the uncertainty, law firm Rocha, Calderon e Advogados Associados created a dedicated webpage to answer frequently asked questions about the changes. Daily visits jumped from roughly 700 to more than 2,000 after the amendment was enacted, overwhelming the firm’s server and temporarily taking the page offline.

Fabiano Zavanella, a labor lawyer at the firm, said the most common question is whether the two weekly days off must be consecutive or can be taken separately. The latter is permitted. Employers have also asked whether they can introduce arrangements that redistribute the two weekly rest days throughout the month, a practice he believes could trigger litigation.

Clients are also seeking clarification about the transition to a 42-hour workweek beginning December 16, particularly whether arrangements involving shifts longer than eight hours can be negotiated directly with individual employees.

“No, that must be negotiated through a collective bargaining agreement,” Zavanella said, adding that “the biggest rush now is to engage with unions and understand how to negotiate.”

Collective bargaining challenges

Estevão Mallet, founding partner of labor law boutique Mallet Advogados, confirmed an extraordinary increase in inquiries, particularly since the amendment’s approval, which left businesses facing what he described as an “abrupt” transition.

“A company operating multiple shifts, such as a food manufacturer using a seven-days-on, seven-days-off schedule, needs not only to hire workers but also to train them, and that takes time,” he said.

Collective bargaining talks remain at a very early stage, Mallet said.

“The most likely outcome is that these negotiations will fail, the new rules will take effect, and workers’ unions will begin demanding additional benefits, such as higher profit-sharing payments, as a condition for reaching an agreement,” he said.

Mallet believes the amendment’s wording, which he considers poorly drafted because it received insufficient scrutiny, is contributing to both the flood of inquiries and the risk of legal disputes.

“We received more than 30 inquiries on this issue alone in October, far above normal levels,” he said. “We set up a dedicated advisory team just to handle it.”

The lawyer expects substantial litigation in the coming months.

“For specialized work arrangements, such as those on offshore oil platforms and in aviation, the government acknowledges the need for separate regulations. But no decree has been issued, and Amendment 141 itself says these arrangements must be regulated by law,” he said.

Mallet also expects the elimination of the six-day workweek to generate more litigation in Brazil than in other countries.

“Brazilian law requires two paid rest days per week, and any compensation for hours worked must take place within the same calendar month, or the employer faces a fine,” he said.

Holiday season pressures

The approaching Christmas shopping season is expected to intensify demand for legal advice throughout November and December, said Tatiana Modenesi, a lawyer at Bruno Freire Advogados.

“This is particularly true for retailers, since stores typically extend their opening hours and hire temporary workers, a measure that will become even more important during the transition under Constitutional Amendment 141,” she said.

Modenesi expects legal disputes to arise when employers seek to eliminate bonuses established under existing collective bargaining agreements as part of negotiations to adapt to the end of the six-day workweek.

“Demand for advisory services at our firm has already risen by about a third,” she said.

Small retailers have been particularly active in seeking legal assistance.

“They will either stop opening one day a week, usually the slowest trading day, or the owner will give up taking Saturdays off, work that shift and keep one assistant instead of two,” Modenesi said. “But there is a risk of losing customers because, in cities like São Paulo, people are very accustomed to having stores and services available seven days a week.”

For employers considering ignoring the new rules because they doubt enforcement by Brazil’s Labor Prosecutor’s Office (MPT), Modenesi warned that public awareness is already widespread.

“Everyone is talking about this issue,” she said. “Workers themselves are well aware of the changes. Failure to comply with the amendment could lead to frustration because everyone wants more time off, and if someone files a complaint, the administrative fine could be substantial.”

High-income employees

Marília Minicucci, a lawyer at Chiode Minicucci, has been warning clients about a separate provision affecting employees whose monthly compensation equals or exceeds two and a half times the maximum social security benefit, or R$21,188.

Under Constitutional Amendment 141, these employees are exempt from rules governing working hours and time tracking, unless the employer voluntarily applies them or they are required under a collective bargaining agreement. This provision is already in effect.

Minicucci said companies that currently track the working hours of employees in this income bracket must immediately adjust their employment contracts.

The concern stems from court precedents establishing that preserving more favorable employment conditions could make their subsequent removal an “adverse contractual change,” potentially rendering the amendment to the contract invalid.

“Prolonged maintenance of more favorable conditions can create legal obstacles to removing them later,” she said.

A recent ruling by the First Panel of Brazil’s Superior Labor Court supports that interpretation (case No. 326-45.2021.5.08.0011).

Payroll costs

At law firm Demarest, lawyers are examining another provision of Amendment 141 with direct implications for payroll expenses: the divisor used to calculate hourly wages for salaried employees, which also determines overtime pay.

“Under the rules of Amendment 141, the divisor will change, making the hourly wage more expensive,” said Celso Baez do Carmo Filho, a partner in the firm’s labor practice.

Carmo estimated that the workload of Demarest’s 10-member labor advisory team has increased by roughly 20% to 30% since October 16.

Most inquiries have come from retailers, industries with continuous operations and healthcare companies.

“A factory that used the six-days-on, one-day-off model, even under a collective bargaining agreement, is moving toward three-on, three-off; four-on, four-off; or two-on, two-off arrangements that accommodate round-the-clock operations,” he said.

“The number of hours worked per day is likely to increase, but the 40-hour weekly limit and two weekly rest days will remain in place. Under a four-on, four-off arrangement, for example, each employee works nine or 10 hours a day and then has consecutive days off. That is legal as long as it is agreed upon with the union,” Carmo said.

“However, most companies have not yet reached the stage of negotiating with unions.”

Union preparations

The Unified Workers’ Central (CUT), one of Brazil’s leading labor federations, and other union organizations have published a guidance booklet for affiliated unions, with legal assistance from LBS Advogadas e Advogados.

Among its recommendations is that unions immediately review existing collective bargaining provisions and formally notify employers or employer associations to request negotiations on amendments to current agreements.

The booklet also advises unions to “assess the suitability of national sectoral bargaining forums and negotiations by industry or business segment.”

LBS recommends that unions preserve provisions that are more favorable to employees, including shorter working hours already secured under existing agreements.

*By  Laura Ignacio and Luiza Calegari — São Paulo

Source: Valor International

https://valorinternational.globo.com/


Fernando Gonçalves — Foto: Gabriel Reis/Valor

Fernando Gonçalves — Photo: Gabriel Reis/Valor

Brazil’s Central Bank halted its interest rate-cutting cycle on Wednesday (Nov. 4), keeping the benchmark Selic rate at 13.75% in response to a recent deterioration in inflation expectations. While the decision by the Monetary Policy Committee (Copom) appeared conservative, its accompanying statement offered no guidance on what might come next. Policymakers also stopped short of signaling that they could raise rates if the inflation outlook worsens further.

The decision ended a series of five consecutive 25-basis-point cuts that began in March. The worsening inflation outlook since the presidential election prompted the shift, in line with expectations from most economists surveyed by Valor last week.

Copom said monetary policy had become more challenging, requiring “composure and caution” in light of “a substantially restrictive Selic rate, a significant increase in uncertainty surrounding the baseline scenario, higher inflation expectations, and a more pronounced slowdown in domestic economic activity.”

Policymakers acknowledged that inflation expectations had drifted further away from the 3% target, including over longer horizons, a development that “contributes to price formation and increases the cost of disinflation.” At the same time, the committee emphasized the impact of “supply shocks” on its inflation forecast for the relevant monetary policy horizon. That projection rose to 3.5% for the second quarter of 2028, from 3.2% for the first quarter of that year.

Mixed signals

For Fernando Gonçalves, head of economic research at Itaú Unibanco, those qualifications played down the deterioration in inflation expectations revealed by the latest Focus survey more than was warranted.

“I would say [the statement] was less hawkish than we expected, even though it conveyed the message that bringing inflation back to target will be challenging,” he said.

Gonçalves believes Copom sought to offset the worsening inflation forecasts by emphasizing both the influence of supply shocks and its assessment that the Selic remains “substantially restrictive.”

“This is not a statement that sends the message that interest rates will stay high for longer. It leaves things open and focuses on describing the uncertainties, even pointing to conflicting signals,” he said.

He cited the committee’s description of economic activity slowing “more sharply” and a labor market showing “signs of cooling at the margin,” despite remaining resilient.

“In a way, it creates room to look through this substantial deterioration in forecasts, since part of it stems from supply shocks and the Focus survey still points to a declining path for the Selic,” Gonçalves said.

In his view, the statement suggests that the bar for raising interest rates is quite high, while leaving open the possibility of further cuts depending on how economic conditions evolve.

Cláudio Ferraz, chief economist at Galapagos Capital, shares that interpretation, suggesting Copom may have sought to discourage speculation about a potential rate increase. Still, he cautioned that more details would emerge only with the release of the meeting minutes next week.

“Taken as a whole, it was the right decision and a tough statement, but as I said, those references did not go unnoticed,” Ferraz said, referring to the Central Bank’s characterization of the Selic as “substantially restrictive” and its acknowledgment of slowing economic activity.

Fiscal uncertainty

Galapagos expects the Selic to remain unchanged over the coming months. Ferraz believes any discussion of renewed rate cuts will have to wait until the second half of the year, once the reelected government has clarified its fiscal policy.

“As fiscal uncertainties are addressed, that could perhaps have a positive impact on asset prices, potentially halt the process of inflation expectations becoming unanchored and, ideally, eventually lead to their reanchoring. Then, given the slowdown in economic activity, it might be possible to discuss a scenario in which interest rates could be adjusted again. But that is not yet on our radar,” he said.

Roberto Padovani, chief economist at Banco BV, described Copom’s statement as “concise” and “cautious.” He said policymakers acknowledged that monetary policy had become more difficult to manage without offering clues about their next steps.

Padovani also pointed to uncertainty over the incoming administration’s economic policies as a reason for the committee’s restrained language.

“We have just come out of an election, and both the Central Bank and analysts are still waiting for information,” he said.

Although investors may interpret the statement as relatively “dovish,” signaling an inclination toward lower interest rates, Padovani argued that the Central Bank needs more information before it can take a clearer position.

“I understand that the Central Bank does not have enough information to issue a much more forceful statement. We need to know what kind of fiscal policy we are going to have. The Central Bank cannot and should not anticipate that. It cannot keep reacting to short-term tensions,” he said.

A more hawkish reading

Camila Faria Lima, chief economist at Canvas Capital, offered a different interpretation, describing the statement as slightly more hawkish. In her view, the decision to halt rate cuts was itself a significant signal, particularly given the committee’s acknowledgment of the deteriorating inflation outlook.

Faria Lima said Tuesday’s Focus survey had prompted her to revise her baseline forecast from a further 25-basis-point cut to the decision Copom ultimately made: holding the Selic steady. With inflation expectations worsening, she concluded that the argument for another reduction was no longer tenable.

“The Focus survey showed very clearly that inflation expectations were becoming even more unanchored, almost as if a sharper slowdown in economic activity did not matter. The fact is that we are facing greater inflationary pressures and expectations are being called into question even over longer horizons, with everything moving toward 4%. That sent a message that made it very difficult for the Central Bank not to react and simply stick to its flight plan,” she said.

Faria Lima therefore sees the communication as more forceful, although she acknowledged that references to a sharper economic slowdown and signs of moderation in the labor market softened its tone.

She also highlighted Copom’s decision to raise its inflation forecast for the relevant monetary policy horizon from 3.2% to 3.5%, even as that horizon shifted from the first to the second quarter of 2028.

The economist agreed with the committee’s assessment that monetary policy had become more challenging, caught between a worsening inflation outlook and a more pronounced slowdown in economic activity.

“Ultimately, the committee highlighted opposing forces, which is why it describes the scenario as more challenging. It will have to contend with both,” she said.

*By Hamilton Ferrari and Estevão Taiar — Brasília

Source: Valor International

https://valorinternational.globo.com/


Federal Revenue: program prioritizes companies’ good faith, waiving penalties for taxpayers who act transparently — Foto: Marcelo Camargo/Agência Brasil
Federal Revenue: program prioritizes companies’ good faith, waiving penalties for taxpayers who act transparently — Photo: Marcelo Camargo/Agência Brasil

The updated version of the regulations governing the Contribution on Goods and Services (CBS) and the Tax on Goods and Services (IBS), the new consumption taxes established by Brazil’s tax reform, is expected to be released next week, the Federal Revenue Service said Tuesday (3). The absence of this document is one of the outstanding issues raised by experts interviewed by Valor in a report published Tuesday (3).

In the report, tax lawyers questioned whether the country would be able to transition to the new tax system on January 1, as stipulated by the reform, which amended the Federal Constitution, given the lack of documents, systems, and guidance.

“It is not possible to presume a constitutional change,” the Federal Revenue Service said in a statement. “The institution’s guidance remains that implementation will proceed according to the constitutional timetable.”

The agency added that “implementation is moving forward, regulatory instruments continue to be issued, technological solutions are under development, and the country has more than two decades of accumulated experience in tax digitalization to ensure a safe, predictable, and successful transition.”

The agency also said that a compliance program had been established, “prioritizing companies’ good faith and waiving penalties for taxpayers who act transparently and comply with the rules already published.”

Tax lawyers raised concerns about how the so-called assisted tax assessment system will work. It is a type of pre-filled tax return for the CBS and IBS. Under the system, the Federal Revenue Service will provide taxpayers with their tax credits and liabilities. However, taxpayers will not be able to amend the information themselves; they will only be able to approve or reject it.

In response, the agency said adjustments are being made to the system to allow corrections. The first version with this functionality will be available for the January 2027 tax assessment, it added.

Another issue raised was the risk of conflicting interpretations of the CBS and IBS rules. The Federal Revenue Service said federal administrative tax appeals bodies are already prepared to review cases involving the CBS. The agency is also working with the IBS Management Committee, made up of representatives from the states, the Federal District, and municipalities, to share formal tax rulings through common systems and promote consistency in administrative interpretations.

In the judicial sphere, the agency argued that Brazil’s procedural legislation already provides mechanisms to resolve potential jurisdictional disputes between judges and conflicting interpretations, to preserve legal certainty during the transition and preventing inconsistent court decisions.

Experts also pointed out that not all municipal governments are prepared to issue invoices under the new system. According to the Federal Revenue Service, municipalities are gradually joining the system. “Currently, 5,571 government entities—municipalities and the Federal District—have joined the National Electronic Service Invoice (NFS-e) agreement. Of these, 5,466 are already active and operational in the system, representing 98% of Brazilian municipalities,” the agency said.

One expert also noted the lack of invoice templates for rental payments and utility bills for water, electricity, and gas. According to the Federal Revenue Service, these templates are already available.

Another concern was the lack of complete data in the Brazilian Real Estate Registry (CIB), a kind of “tax ID for properties” that will be mandatory for transactions starting next year. Federal Revenue Service data show that the registry is not yet complete. The agency said 3,356 municipalities have joined the registry, including all state capitals except Macapá, in Amapá state. More than 24.5 million CIB numbers have already been issued.

Experts also raised concerns about the 11.3% reference rate for the CBS calculated by the Federal Court of Accounts (TCU), which is under review in the Senate. In response, the Federal Revenue Service said the figure is a reference rate designed to ensure revenue neutrality, but “does not correspond to the effective tax burden borne by taxpayers.” The actual burden, it said, depends on tax credits generated throughout the supply chain, whether preferential tax regimes and reduced rates apply, and other factors.

One indication that implementation of the reform is progressing, the Federal Revenue Service said, is the number of tax documents already issued under the new system. A total of 3.6 billion documents had been issued as of November 2, representing 86.9% of the total. Data on a government dashboard also show, however, that 23.4% of businesses issuing invoices still do not report CBS and IBS information, while another 27% report it only partially.

*By Lu Aiko Otta and Giordanna Neves — Brasília

Source: Valor International

https://valorinternational.globo.com/


Carlos Silva Filho — Foto: Divulgação
Carlos Silva Filho — Photo: Divulgação

With no major negotiating issue or review of Paris Agreement targets on the agenda, COP31—the United Nations Climate Change Conference taking place from November 9 to 20 in Antalya, Turkey—aims to establish itself as the conference of implementation. The Turkish presidency has selected waste, the circular economy, and zero waste as one pathway for demonstrating practical results.

“This will be the COP of action and implementation,” explained Carlos Silva Filho, special adviser to the COP31 Climate High-Level Champion.

The Brazilian is one of four advisers on the team led by Samed Agirbas, COP31’s climate champion. Silva Filho is responsible for the Sustainable Development and Circular Economy agenda and helped formulate the sector’s targets, announced in September during New York Climate Week.

For waste, the goals are to halve the growth in municipal waste generation by 2035 and raise the global circular-material use rate to at least 15% over the same period. The rate currently stands at 6.9%.

The “Atlas Global de Resíduos Sólidos” (“Global Solid Waste Atlas”), released by the United Nations Environment Programme (UNEP) and the International Solid Waste Association (ISWA) in 2024, projects that solid-waste generation will rise from 2.3 billion tonnes in 2023 to 3.8 billion tonnes by 2050.

Currently, 38% of waste is discarded at unsuitable sites, and only 19% of municipal solid waste is recycled. Zero-waste and circular-economy measures, by contrast, could generate a net annual gain of $108.5 billion.

Silva Filho noted that waste is still regarded as relatively unimportant to the climate agenda because the sector directly accounts for about 3% of global greenhouse-gas emissions. However, studies underpinning the team’s work show that proper waste management could help reduce total emissions by as much as 25% because its effects extend far beyond the sector itself.

Biomethane is one example. Produced from waste, it reduces emissions within the sector and, when used as fuel, also cuts transportation emissions. Recycling is another example. By replacing virgin raw materials, it reduces emissions throughout the supply chain, from extraction to manufacturing, as when recycled aluminum replaces virgin bauxite.

Methane is another concern. “If we do not tackle methane, tackling carbon dioxide will do no good,” Filho warned.

Climate Tinder

Silva Filho recalled that years ago, during a COP meeting about issues to be included in the negotiations, he raised his hand to propose waste and the circular economy but was told the subject was unrelated to the climate agenda. Shortly afterward, at COP28 in Dubai in 2023, the sector secured its first pavilion.

Silva Filho advocates using zero waste and the circular economy as a cross-cutting platform connecting the workstreams of the climate-action agenda inherited from COP30. Those discussions gave rise to the Zero Waste Action Platform, launched in Turkey in June.

The Brazilian described it as a kind of “Tinder for climate action,” connecting initiatives with what they need. “Not everyone needs money. One initiative may need regulatory improvements, while another needs to connect with infrastructure that already exists,” he explained. In his view, this cross-sector connection should be COP31’s greatest legacy.

With no major negotiation at stake, companies have begun to realize that the conference’s results depend on them, Silva Filho noted. “While governments set targets and provide guidance, the private sector carries out the work.”

This year, the conference will feature its own building, the Zero Waste Pavilion, with three auditoriums and 180 plenary sessions planned. Zero Waste Day will be held on November 11, coinciding with the leaders’ summit. The program includes a panel on biomethane featuring Brazilian company Orizon.

“These are not projects from someone who had an idea and wants to get it off the ground. This is what the waste sector is already doing in practice,” Filho emphasized. Rio de Janeiro has already announced that it wants to join the zero-waste districts through an initiative to divert organic waste from landfills. The team is also working to ensure that the final Antalya declaration recognizes proper waste management and zero waste.

The Brazilian government brought the recently approved “Estratégia Nacional de Economia Circular” (“National Circular Economy Strategy”) to the discussions and presented Recircula Brasil. This online system tracks the materials chain to measure whether the global 15% circularity target is being met.

Domestically, however, Brazil is still moving slowly. The country’s waste-recovery rate is around 4% to 5%, according to Silva Filho. “The regulatory and technological framework is ready. We need to put it into practice,” he argued.

Financing is one of the bottlenecks. According to Silva Filho, the main challenge is not only investing in infrastructure but also funding the long-term operation and maintenance of facilities such as waste-treatment plants, for which no funding source exists. Alternatives under discussion include carbon or methane credits and mechanisms that hold producers responsible for what they place on the market.

*By Naiara Bertão — São Paulo

Source: Valor International

https://valorinternational.globo.com/


Homero Guizzo — Foto: Ana Paula Paiva/Valor
Homero Guizzo — Photo: Ana Paula Paiva/Valor

After bets on Selic rate cuts reversed in financial markets following the surprise outcome of Brazil’s presidential election runoff, analysts are now forecasting an even more challenging 2027 for economic growth. Expectations that the benchmark interest rate will remain unchanged for an extended period, or even rise again, add to signs that economic activity is losing momentum more rapidly this semester, reducing the statistical carryover into next year.

In a revised outlook released Friday (30), Itaú Unibanco said it now expects GDP to grow 1.6% this year, down from its previous forecast of 1.7%. For 2027, it cut its estimate from 1.2% to just 0.5%.

“The revision reflects the incorporation of higher interest rates and weaker economic activity over the coming year. The need to maintain restrictive monetary conditions for longer is expected to intensify the cumulative effects of monetary tightening on consumption, investment and credit conditions,” wrote the team led by former Central Bank director Diogo Guillen. The bank now expects the Monetary Policy Committee (Copom) to halt its rate-cutting cycle and keep the Selic policy rate unchanged at 13.75% through the end of 2027, in an effort to curb inflation, which it projects will reach 6.1% by the end of next year.

Economic weakness and high inflation “limit growth in real income and consumption, with a particularly significant impact on lower-income households. At the same time, high household debt makes consumption more sensitive to tighter financial conditions. Against this backdrop, we expect domestic demand to remain sluggish in 2027, with the balance of risks to growth still skewed to the downside,” Itaú said.

ABC Brasil has also removed Selic rate cuts from its baseline scenario through the end of 2027. “With tighter financial conditions and less fiscal stimulus, we have lowered our GDP growth estimate from 1.9% to 1.7% in 2027 and to 1% in both 2027 and 2028,” the bank said. It had previously forecast growth of 1.5% for 2027 and 1.6% for 2028.

President Lula’s election victory on Sunday (25) caught much of the market off guard and triggered a sharp sell-off in domestic assets, prompting analysts to revise their forecasts. With expectations that the necessary fiscal adjustment will not materialize, risk premiums have risen, as have longer-term inflation expectations. Despite Central Bank interventions, the dollar rose 9.04% last week, its biggest weekly gain since the 2008 financial crisis. The benchmark stock index Ibovespa also posted its steepest weekly loss since the pandemic. In the interest-rate market, 10-year yields climbed back above 15%.

“The selloff in Brazilian assets poses a greater threat to growth than to inflation in the country,” Capital Economics said in a report. “The most immediate effect will be exchange-rate pass-through to inflation, but this should be limited. If the exchange rate remains at current levels, the pass-through should add 0.3 percentage points to headline inflation over the next six months,” analyst Liam Peach wrote.

The greater threat comes from tighter financial conditions, he said. “The economy is vulnerable to higher interest rates because of the deterioration in public- and private-sector debt. Household debt service has reached a new record of 29% of income, while borrowing costs and corporate defaults are at historically high levels. Even if Copom keeps the Selic rate unchanged at its next meetings, borrowing costs are likely to rise. Combined with the fact that the economy was already showing signs of slowing before the election, tighter financial conditions reinforce our forecast that GDP growth will decelerate to 1% next year.”

Asset manager ASA has an even gloomier outlook. Although it still expects further rate cuts by the end of 2027—forecasting that the Selic rate will resume its decline at some point between the second and third quarters—it has cut its GDP growth forecast for next year from 1% to zero. The revision reflects the delayed impact of measures announced this year, “regardless of any fiscal measures that may eventually be announced.” The firm also warns of a risk of recession, depending on how economic agents respond.

“Without expectations of a credible fiscal adjustment, inflation expectations are likely to remain unanchored, and may even deteriorate further, making the Central Bank’s job more difficult. The monetary authority is expected to resume rate cuts only around mid-2027, as the sharper loss of momentum in domestic activity becomes more evident. In any case, the new reality will involve a higher neutral interest rate, with the Selic ending 2027 at 13%,” ASA said.

“In this scenario, with lower GDP growth, interest rates remaining at higher levels and technical and political obstacles to a faster fiscal adjustment, we project a further deterioration in the trajectory of gross public debt, which is expected to rise more rapidly in the coming years. We forecast general government gross debt at 88.5% of GDP in 2027, a new record for the series, surpassing the level reached during the pandemic.”

At Terra Investimentos, the expectation is that worsening inflation forecasts in the Focus survey will feed into the Central Bank’s own projections and force policymakers to raise interest rates in 2027, even as the economy undergoes a pronounced slowdown.

“We were already working with an inflation forecast above the market median for next year, at around 5.3%, because we were factoring in effects that no elected government can control, such as the impact of El Niño on food prices. But there was some expectation that a new government might offer a more constructive approach to fiscal policy, help anchor expectations and stabilize the exchange rate, which would help keep industrial goods and services prices in check. Without that, our forecast rises further,” said Homero Guizzo, the brokerage’s chief economist. He currently forecasts a Selic rate of 14.50% and IPCA inflation of 5.7% next year, but stressed that the estimates are preliminary and could rise.

With higher benchmark interest rates and a likely deterioration in the business environment, Guizzo has also provisionally lowered his GDP growth forecast for next year from 1.2% to 0.9%. “The main factor behind the slowdown will be developments in the credit market, which has been deteriorating for some time. More investment and consumption plans will be put on hold,” he said. The slowdown will be less severe only because the next government’s fiscal policy is expected to remain expansionary, preventing a sharper contraction in economic activity, he added.

*By Marcelo Osakabe — São Paulo

Source: Valor International

https://valorinternational.globo.com/