One year after the collapse of Banco Master, the 18 state and municipal pension funds that invested in the bank are still grappling with their losses. Of the roughly R$4.6 billion placed in financial bills (LFs) or in funds managed by the liquidated institution, R$3.7 billion belonged to Rioprevidência. The fund, which serves more than 230,000 civilian and police state workers in Rio de Janeiro, has recovered R$1.4 billion through the courts. The rest of its investment, along with those of the other public-sector pension systems, particularly the amounts placed in LFs, remains in Master’s creditor queue.

Unions and associations have raised the possibility of state and municipal governments injecting funds into the pension funds to cover the shortfall, but no steps have been taken in that direction. In Rio de Janeiro, according to the State Finance Department, the state Treasury has not contributed to Rioprevidência to pay retirement and survivor benefits since 2021. The department said no contributions are planned for 2026 or included in the 2027 Annual Budget Bill.

A new management team took over Rioprevidência after the fund’s president was arrested in January and overhauled its structure. State attorney Felipe Derbli de Carvalho Baptista was appointed to lead it and carried out a comprehensive review. Positions in the administration and finance, social security and investment departments, for example, were made exclusive to career civil servants.

In December 2025, the Rio de Janeiro State Attorney General’s Office (PGE-RJ) obtained a court order allowing it to withhold payments owed to Master and PKL One Participações S.A. in connection with payroll-deductible loans taken out by public employees, and to place the funds in a Rioprevidência account. The transfers will be suspended for about 20 months, or until the total reaches R$970 million, the amount Rioprevidência invested in Master’s financial bills.

The defendants are barred from taking any action against active and retired public employees who took out loans through CredCesta, including reporting them to credit bureaus or filing claims over unpaid debts. Deivis Antunes, the former president under whose administration the fraud took place, is being held at Pedrolino de Oliveira Prison in Bangu.

“The remaining amounts are the subject of lawsuits filed by PGE-RJ, which have already secured the deposit of funds from the withholding of payroll-deductible loan payments, as well as the freezing of assets belonging to all defendants,” the state government disclosed in a statement to Valor.

The statement added that the fund had adopted “measures to improve governance and compliance mechanisms, with the aim of strengthening internal controls and investment security.” It also stressed that retirement and survivor benefits are guaranteed.

The other public-sector pension systems are seeking compensation through the courts. According to the Ministry of Social Security (MPS), the largest investment after Rioprevidência’s was made by Amapá Previdência (Amprev), which put R$400 million into the bank.

The figures cover investments made between October 2023 and December 2024. The Amazonas state pension system invested R$50 million. The list also includes 15 municipalities, among them Aparecida de Goiânia, in Goiás state, which invested R$40 million, and Maceió, in Alagoas state, with R$97 million.

In a statement, Maceió Previdência said it had filed a claim for its credit in the liquidation proceedings. The fund said it has assets of R$1.6 billion and that its losses from the Master case do not affect its ability to meet its obligations. “Maceió Previdência reaffirms that retirement and survivor benefits are guaranteed, and that payments have not been affected by the investments made in Banco Master.” The other pension funds did not immediately respond to requests for comment.

*By Liane Thedim — Rio de Janeiro

Source: Valor International

https://valorinternational.globo.com/


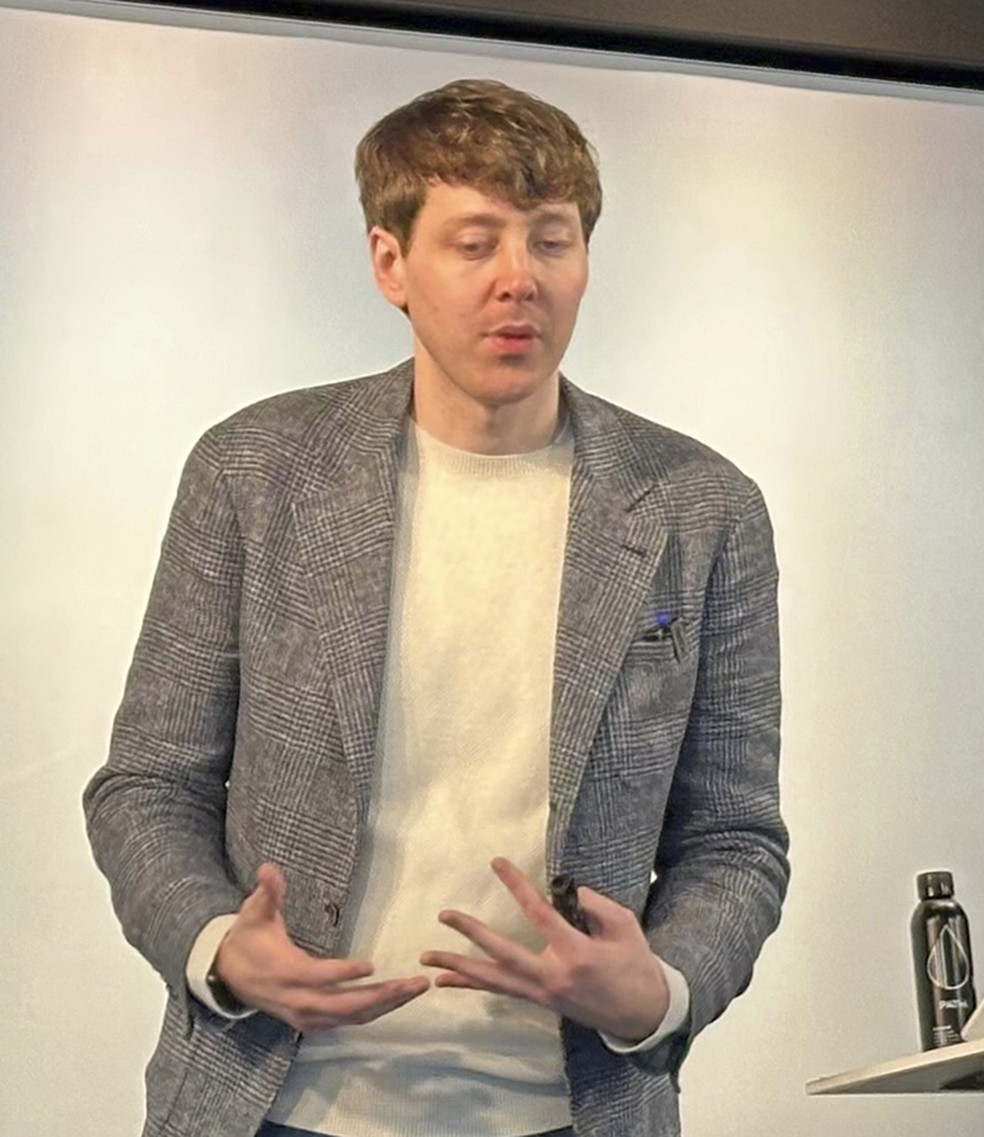
Marco Freire — Foto: Ana Paula Paiva/Valor
Marco Freire — Photo: Ana Paula Paiva/Valor

Mounting concerns over economic policy during President Luiz Inácio Lula da Silva’s fourth term triggered a sharp sell-off in Brazil’s currency and interest rate markets on Monday (Nov. 16). With no sign of a fiscal adjustment capable of stabilizing public debt and uncertainty surrounding the composition of the next administration, the real weakened dangerously close to R$5.80 per dollar, hitting a 19-month low. Interest rate futures surged, pushing yields back above 15% across several maturities.

The exchange rate per U.S. dollar rose 2.15%, closing at R$5.77, its weakest level since April 17, 2025, when it ended the session at R$5.80. It was the worst performer among the 33 most liquid currencies monitored by Valor

In the interest rate market, the yield on January 2029 interbank deposit (DI) futures jumped to 15.01% from 14.67%, while the January 2037 contract rose sharply to 15.30% from 15.10%.

Fiscal resistance

Several factors compounded investors’ unease over Brazil’s economic policy, starting with resistance from left-wing factions to a supplementary bill designed to generate R$50 billion to R$60 billion in savings to meet the 2027 fiscal target. Markets already consider the proposal modest, and opposition to it has reinforced the perception that a more substantial fiscal adjustment is unlikely.

“The country is facing a massive storm at a time when the U.S., the UK and the eurozone are raising interest rates. Yet there seems to be a feeling in Brasília that doing nothing is an option. It isn’t. If the Workers’ Party [PT] is fighting over an ‘irrelevant’ adjustment, imagine what would happen if something more significant needed its support,” said a portfolio manager who requested anonymity.

Investors also reacted negatively to proposals from PT lawmakers in the Lower House to increase taxes on profits and dividends, tax currently exempt financial instruments such as real estate and agribusiness credit notes (LCIs and LCAs), and raise taxes on interest on equity payments (known as JCP). The measures were unveiled Friday evening, but their impact on markets was only felt on Monday.

Adding to the turmoil were rumors that Aloizio Mercadante, president of the Brazilian Development Bank (BNDES), could become finance minister—an possibility he denied. Markets continued to deteriorate despite his denial, reflecting investors’ waning appetite for Brazilian assets.

Currency overshooting

Amid growing concerns about Brazil’s economic outlook, traders pointed to position adjustments and the possible triggering of stop-loss orders, designed to limit losses when an asset reaches a predetermined price.

On Friday, foreign investors had already increased their bets against the real, bringing their long dollar positions against the Brazilian currency in the derivatives market to R$74.4 billion, the highest level since late 2024, when the exchange rate per dollar reached a nominal record of R$6.30, Valor found.

Joseph Incalcaterra, head of Latin America macro strategy at HSBC, said investors’ biggest fear now is a repeat of the currency overshooting seen two years ago.

“It’s very much on investors’ minds. It comes up frequently in our meetings outside Brazil. People are asking how similar the current situation is to 2024. And yes, I think many investors see a lot of similarities,” he warned.

“That episode was ultimately driven by disappointment with fiscal policy. The global environment was highly uncertain, and December was a seasonally unfavorable month for the currency because of dividend-related outflows. That’s on a lot of people’s minds now, and perhaps that’s why we’re not seeing much interest in the real,” Incalcaterra said.

He attributed the heightened caution to an increase in public spending in recent months, which has worsened the fiscal outlook.

“Until investors really understand how these measures will be accounted for and whether they will be offset by other measures, we won’t see a more substantial recovery in the currency,” he said.

Incalcaterra expects market participants to view the coming weeks as a “difficult” period for Brazilian assets, at least until December, when greater clarity on the 2027 budget is expected.

Rate hike expectations

The turmoil in the interest rate market prompted a significant repricing of expectations for Brazil’s Central Bank’s upcoming monetary policy decisions. The forward curve began pricing in a roughly 10-basis-point increase in the benchmark Selic rate at the next Monetary Policy Committee (Copom) meeting on December 9.

For 2027 as a whole, interest rate futures began pointing to around 170 basis points of tightening, which would take the Selic to nearly 15.5%, above its recent peak of 15%.

Speaking to reporters after recording the “Horizontes 2027” podcast, Marco Aurelio Freire, who oversees liquid funds at Kinea Investimentos, said the current environment poses significant challenges for investing in Brazil, given the lack of consensus within both the government and Congress on the need for a more substantial fiscal adjustment.

Political obstacles

Even if Lula appoints a more centrist finance minister willing to restore fiscal discipline, Freire said, there is no guarantee that such an adjustment will materialize.

“We may be anxiously waiting to see who gets appointed, but the person alone won’t solve the problem,” he said.

“And then there’s another question: even if the people appointed are good, is the president convinced that spending needs to be put on a lower trajectory? And if he is, can you get it through Congress?” Freire asked.

He sees little support in Congress for a broader fiscal adjustment agenda, which is unlikely to gain traction unless financial stress becomes more severe.

“I think the risks here are considerable. We may see small measures that calm things down in the short term, but getting to the point where the president and Congress are convinced of the need to cut public spending … I think we’re still a long way off,” Freire said.

*By  Gabriel Caldeira  and Arthur Cagliari — São Paulo

Source: Valoar International

https://valorinternational.globo.com/
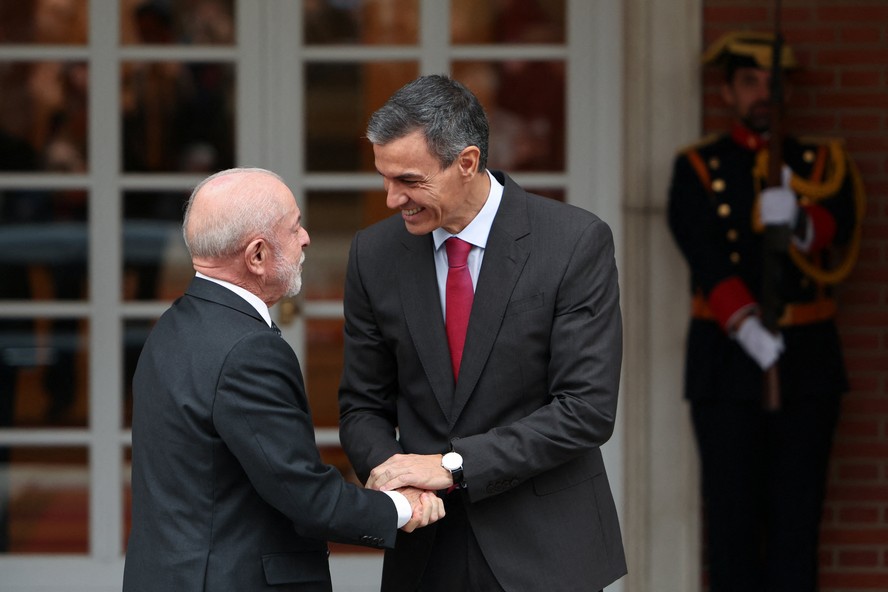


President Lula greets Spanish Prime Minister Pedro Sánchez in Madrid

President Lula is moving to contain a political and financial backlash over his government’s proposed fiscal adjustment, with left-wing allies denouncing the measures as a betrayal of campaign promises and investors questioning whether they go far enough to stabilize Brazil’s public finances.

Back in Brasília after a week in Asia, Lula is expected to meet economic officials and congressional leaders on Tuesday (17) to contain the dispute and secure passage of a package the government estimates will have a R$60 billion impact on the 2027 budget. The political turmoil has coincided with a sharp selloff in Brazil’s currency, which fell 2.15% against the dollar on Monday.

The government’s position, endorsed by Lula, is that the proposal does not amount to the sweeping spending cuts his campaign attributed to plans put forward by Senator Flávio Bolsonaro of the Liberal Party during the presidential race, nor does it constitute the betrayal of voters alleged by some of his own supporters. Economists and financial market participants, meanwhile, regard the package as insufficient to address Brazil’s fiscal problems.

Lula is expected to meet Planning Minister Bruno Moretti, who drafted the proposal, along with other senior officials, including Finance Minister Dario Durigan and Chief of Staff Miriam Belchior.

Lula is also expected to meet with officials responsible for relations with Congress, including government leaders in the legislature and Institutional Relations Minister José Guimarães. According to people familiar with the discussions, Lula remained in contact with ministers in Brasília during his trip to Asia last week to keep abreast of the bill’s progress through Congress.

Another possible meeting would bring together Moretti and government allies in Congress, including Workers’ Party lawmaker Paulo Pimenta, the government’s leader in the Lower House, to explain the measures and discuss how best to defend them.

As part of the administration’s efforts to ease resistance to the package, Vice President Geraldo Alckmin met Monday (16) with organizations that had issued a manifesto opposing public-sector salaries exceeding the constitutional pay ceiling.

After the meeting, Alckmin said there was no “solid reason” for the sharp fluctuations in the Brazilian Real seen throughout the day. The U.S. currency closed 2.15% higher at R$5.7767, its highest level since April 17, 2025.

Beyond the market reaction, dissatisfaction with the fiscal package has also spread across social media.

A WhatsApp channel called “Lula’s Army,” created during the presidential campaign to mobilize supporters, has become one outlet for that discontent.

In response to posts by Congressman André Janones of the political party Sustainability Network (Rede), who runs the channel, participants have reacted with scissors emojis, accusing Lula of pursuing sweeping spending cuts.


Tuesday’s meetings were still being arranged and had not been officially announced by the presidential palace. The Finance Ministry, however, confirmed that Durigan would meet Pedro Uczai, the Workers’ Party leader in the Lower House, at 4:30 p.m.

The government’s priority is to resolve the internal dispute and secure congressional approval.

Mounting pressure from left-wing groups against the fiscal adjustment bill has raised doubts about the administration’s ability to advance more far-reaching reforms.

The government estimates that the measure will have a R$60 billion fiscal impact in 2027.

Officials fear that if Lula is already struggling to pass legislation primarily intended to ease pressure on next year’s budget, he could encounter even greater resistance to the more ambitious constitutional amendment his administration is considering proposing afterward.

Some government officials believe that without such a structural adjustment, the real could plunge further.

According to people interviewed by Valor, advancing the fiscal agenda will also require Lula to decide who will lead the Finance Ministry during his fourth term. With no decision yet made, the president is expected to turn his attention to the appointment in the coming days.

Despite the uncertainty over the ministry’s leadership, government officials believe the fiscal adjustment will continue regardless of who takes the post.


Because the broad outlines of the fiscal agenda have already been presented to Lula and discussed with ministers and lawmakers, the measures are now regarded as a government initiative, although the design of future proposals will depend on the choice of finance minister.

Behind the scenes, members of the current economic team favor discussing a constitutional amendment that could, among other measures, limit spending currently excluded from Brazil’s fiscal framework.

Such expenditures include those of Fundeb, the country’s main public education funding mechanism, and the Federal District Constitutional Fund, which finances public services in the capital region.

Resistance to the fiscal adjustment bill has intensified in recent days, including amid interpretations that the proposal could affect minimum wage increases.

The controversy centers on a provision stipulating that, in fiscal years when the government activates spending restraints under Brazil’s Fiscal Responsibility Law and an additional mechanism intended to bring the budget balance toward the center of its fiscal target, real spending growth would be capped at 2%, rather than the 2.5% permitted under the fiscal framework. In 2027, the difference would amount to R$12.8 billion.

The lower limit, however, would apply only to the fiscal year in which the restriction was activated and would not reduce the base used to calculate spending ceilings in subsequent years.

According to the government, the 2% limit would restrain expenditures during budget execution, rather than in preparing the annual budget, which would continue to assume a real spending growth ceiling of 2.5%.

Under the federal government’s interpretation, the measure would therefore neither change the rate used to prepare the budget nor affect annual minimum-wage increases.

The Senate approved the bill’s main text last week by a vote of 45 to 31. Senators are expected to consider amendments and provisions requiring separate votes on Tuesday.

Beyond the fiscal adjustment, Lula must also settle his cabinet’s future composition and decide which legislative proposals should go to a vote before the current Congress completes its term. His agenda could also include a Supreme Court nomination.

Another meeting scheduled for Tuesday is expected to finalize a provisional measure creating the Ministry of Public Security, with a candidate already selected to head the new department.

The approved constitutional amendment on public security is expected to be formally enacted next week.

Crisis at the Federal Police

Another issue awaiting Lula is the crisis at the Federal Police, which escalated during his absence.

As Valor reported, government members have expressed dissatisfaction with Federal Police Director General Andrei Rodrigues‘s performance and have not ruled out replacing him.

Allies also say Lula is expected to decide who will head the Finance Ministry by the end of the month at the latest.


According to presidential palace officials, Lula has not yet taken a position on the matter. However, Durigan’s involvement in the administration’s current legislative initiatives has strengthened his prospects of remaining in the job.

On the legislative front, government interlocutors have not ruled out a meeting in the coming days with Senate President Davi Alcolumbre of Brazil Union to discuss both the fiscal adjustment and the nomination to fill the Supreme Court seat vacated by Justice Luís Roberto Barroso more than a year ago.

The presidential palace is concerned about securing votes on important measures before newly elected lawmakers take office, as the incoming Congress will have an even more conservative profile.

*By Lucas Borges Teixeira, Giordanna Neves and Sofia Aguiar, Valor — Brasília

Source: Valor International


Charles Lamanna, Microsoft’s executive vice president for Copilot, agents, and platform, apologized on behalf of the company — Foto: AP
Charles Lamanna, Microsoft’s executive vice president for Copilot, agents, and platform, apologized on behalf of the company — Photo: AP

The longest outage ever to hit Microsoft’s communications, productivity, and security services disrupted businesses, public services, and consumers in 74 countries for 17 to 21 hours, depending on the location, from Thursday (12) to Friday.

The global outage, which affected software including Outlook, Teams, and Office 365 applications, was felt in healthcare, government agencies, financial operations, the publication of earnings results, and communications within legislatures and the judiciary.

In Brazil, the National Council of Justice (CNJ) and the Federal Supreme Court suspended procedural deadlines because of the outage, following a request from the Federal Council of the Brazilian Bar Association (OAB). The OAB said the failure made it difficult for lawyers to access the system to file legal petitions. The count of deadlines is expected to resume on Monday.

Britain’s National Health Service (NHS) switched to alternative technology systems or paper records to keep its workflows running during the outage. The disruption also affected the U.S. House of Representatives, airline customer support operations, and financial markets, Reuters reported.

The outage disrupted the flow of messages at Euronext, the European stock exchange operator, while in Taiwan, asset managers and insurers saw their operations interrupted.

Using a simple calculation of productivity losses per company, André Gaio, a professor at FIA Business School, estimates that an organization with 1,000 employees who lost access to Microsoft email and communication tools would lose R$400,000. The estimate assumes “an average hourly cost of R$80 and half of the work being stalled for ten hours,” Gaio explains. “That does not include lost sales or missed deadlines with a client or regulatory agency,” he said.

Early Friday afternoon, Microsoft said the problem stemmed from a technical failure unrelated to cybersecurity, artificial intelligence, or AI agents.

“The incident was triggered by an issue that occurred during an earlier expansion of network capacity and came to light following a recent infrastructure change. We have resolved the root cause and are continuing to restore service for customers and regions that are still affected,” the company said in a statement. Microsoft added that it would publish a full report on the incident once its investigation was complete.


A network capacity upgrade is an intervention a company carries out so its infrastructure can carry more data, process more requests, or sustain more simultaneous connections, explains Marcelo Branquinho, CEO of cybersecurity firm TI Safe. “Technically, this is consistent with a latent defect: for example, an incompatibility that only emerges when a particular component starts receiving traffic in a different way or operating under different conditions,” he says.

TI Safe estimates that an outage like the one that hit Microsoft applications could cost R$1.47 billion a day, or R$44.2 billion over 30 days. The company said the estimate was based on Brazil’s 2025 gross domestic product (GDP), of roughly R$12.7 trillion, and on assumptions about net production losses over time.

“The discussion about technological dependence needs to go beyond the choice of suppliers and address the ability to keep essential operations running,” Branquinho says. “A company may have its core systems up and running but lose access to digital identity, data, or the integrations it needs to sell, pay suppliers, and serve customers,” he warns.


Gaio, of FIA Business School, notes that the credits Microsoft provides when it fails to meet service-level agreements cover only a small portion of the losses, because the amount “is calculated based on the monthly license fee, not on the customer’s losses.”

He points to past incidents, such as the failure of servers running Microsoft’s Windows operating system, triggered by a CrowdStrike security software update. That incident affected 8.5 million machines and caused $5.4 billion in direct losses for the 500 largest U.S. companies in 2024.

The outage, which lasted more than 17 hours, is the longest in Microsoft’s history, but it is not the first incident this year. In January, Outlook, Teams, and Microsoft 365 services were down for about nine hours. In August, Outlook and Exchange Online also suffered disruptions following a code update by the company.

Besides the communication software in Outlook and Teams, the global failure affected productivity and collaboration applications and cloud-based tools such as Word, Excel, PowerPoint, SharePoint, and OneDrive, as well as the Microsoft 365 Copilot artificial intelligence assistant and the Microsoft Defender security suite.

The outage also caused integration problems between Microsoft 365 and the AI assistants OpenAI’s ChatGPT and Anthropic’s Claude. Microsoft Office 365 has 430 million users worldwide. According to data platform Enlyft, more than 7.5 million companies subscribe to it globally.

Charles Lamanna, Microsoft’s executive vice president for Copilot, agents, and platform, apologized. “We know our customers rely on these services to carry out important work every day, and we regret the impact these disruptions have had on those who depend on us.”

Several companies and brands, including Coca-Cola, Heineken Group, KitKat, Ryanair, Tide, Domino’s, and Wellhub, took a humorous approach to the outage on social media. Coca-Cola’s account, for example, joked about Friday the 13th. On a billboard, the brand displayed the message “Your inbox can wait. Catching up with each other can’t,” alongside an image of a family gathered for a meal. Nestlé’s KitKat chocolate brand used its well-known slogan, “Have a break,” and joked about an Outlook error message on Instagram.

In Brazil, Heineken Group joined in with an image of a laptop displaying error messages next to cans of Fys soft drink, accompanied by the message: “Come on, of all days, it had to happen on a Friday.”

As for markets, Friday was a tougher day for Microsoft shares. They closed slightly higher, up 0.17%, but fell 0.23% in after-hours trading following the close of the Nasdaq session.

*By Daniela Braun, Beatriz Olivon and Bianca Guilherme — São Paulo and Brasilia

Source: Valor International

https://valorinternational.globo.com/


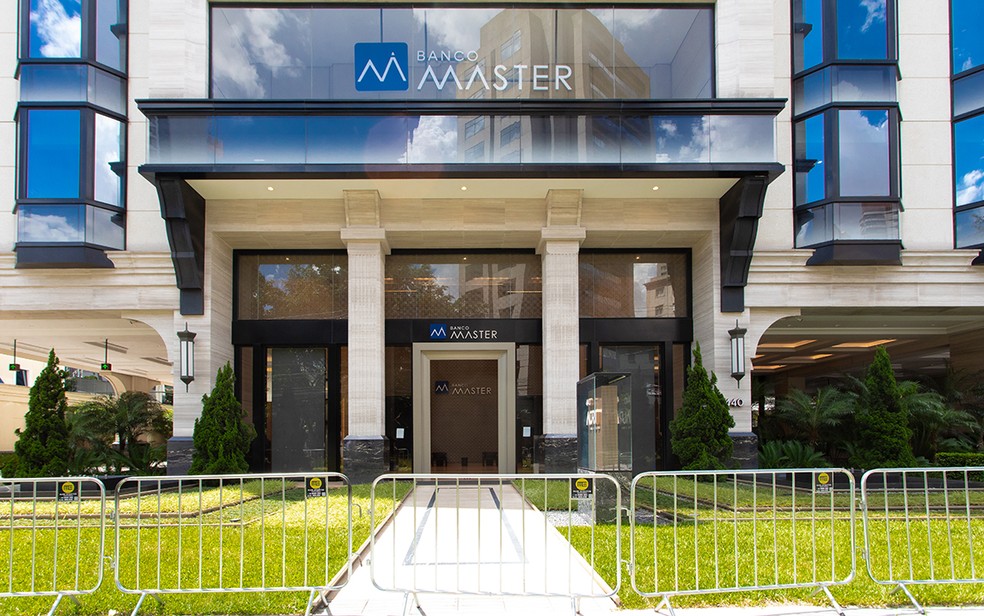
One year after Master's liquidation, investigations continue to expose the extent of its political and institutional connections — Foto: Edilson Dantas/O Globo
One year after Master’s liquidation, investigations continue to expose the extent of its political and institutional connections — Photo: Edilson Dantas/O Globo

Next Wednesday marks one year since the collapse of Banco Master, which has left nearly R$76 billion in losses, based on figures compiled by Valor, and pushed Brazil to the brink of an institutional crisis.

Brazil’s Central Bank ordered the extrajudicial liquidation of Master on the morning of November 18, 2025. The previous evening, Federal Police arrested the lender’s then-controlling shareholder, Daniel Vorcaro.

It marked the end of his unconventional rise as a flamboyant banker, which began in 2017 when he acquired a stake in Banco Máxima. Two years later, Vorcaro took control of the lender, subsequently renamed Banco Master.

Aggressive fundraising

Under its new identity, the bank became a fundraising machine, attracting investors with coverage from Brazil’s Credit Guarantee Fund (FGC) and offering returns of up to 140% of the benchmark interbank deposit rate (CDI), well above the market average.

The strategy enabled Master to raise roughly R$60 billion. Yet little of that money went toward lending, the traditional business of banks. Instead, Master invested in highly illiquid assets, including claims on court-ordered government payments awaiting formal issuance, and assets with artificially inflated valuations. It then channeled the money through a web of investment funds, many of them managed by Reag.

Fallout for BRB

Master’s efforts to sustain its operations amid mounting liquidity constraints in 2024 dragged Banco de Brasília (BRB) into the crisis. The bank, controlled by the Federal District government, purchased fraudulent loan portfolios and subsequently attempted to acquire Master itself. BRB now needs a R$8 billion capital injection that has yet to materialize.

Institutional turmoil

As investigations progress, they are exposing Vorcaro’s ties—many of them improper—to officials across all branches of government and the political spectrum. The scandal has placed Brazil’s Supreme Court (STF) at the center of the storm and, in recent days, sparked a crisis within the Federal Police.

Despite everything that has come to light, many questions remain unanswered. This week, Valor examines the fallout from the first year of the collapse and looks at what comes next.

*By Talita Moreira, Álvaro Campos  and Mateus Coutinho — São Paulo and Brasilia

Source: Valor International

https://valorinternational.globo.com/


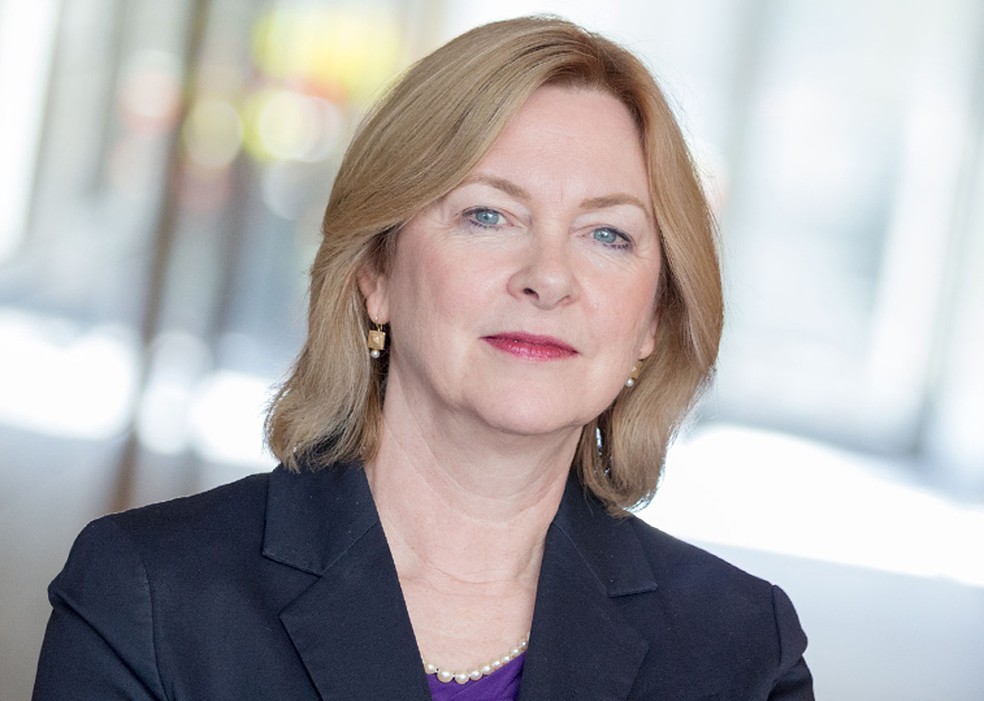
Mary Lovely — Foto: Divulgação
Mary Lovely — Photo: Divulgação

Brazil’s exports to the United States posted their first year-to-date increase in 2026 in October, according to Brazilian government data compiled in the Brazil-U.S. Trade Monitor by the Brazil-U.S. Business Council (Amcham Brasil).

Shipments rose 87% in October from the same month in 2025, reaching $4.3 billion, the highest value for the month in the past decade. As a result, exports in 2026 edged up 0.2% to a total of $31.7 billion.

U.S. data also show that imports of Brazilian products have been increasing since July. In September, the latest month for which figures are available, they totaled $3.7 billion, compared with $2.8 billion in January 2026 and $2.9 billion in September 2025.

According to Brazilian data, the volume of exports rose 99.9% in October from a year earlier, while average prices fell 6.4%. Part of this performance reflects the low comparison base in the previous year, when additional tariffs of up to 50% imposed under the International Emergency Economic Powers Act (IEEPA) were in effect.

October’s results were driven by sales of crude oil and fuel oils, which accounted for 39.2% of Brazil’s exports to the U.S. during the month. Beef also stood out.

Abrão Neto, president of Amcham Brasil, said October’s figures were encouraging but cautioned that some sectors remain heavily affected by tariffs.

Between January and October 2026, exports of products not subject to additional tariffs increased 5.3%, while shipments of goods facing some form of additional tariff fell 5.7%, according to Amcham.

Among the 10 leading products subject to these tariffs, exports of nine declined between January and October. The steepest drops included coniferous wood, unmanufactured tobacco, beef tallow, and processed granite.

Brazilian imports from the U.S. fell 3.4% between January and October, to $36.9 billion, while purchases from the rest of the world increased 8.2%, according to Amcham. The decline was concentrated mainly in manufacturing, extractive industries, and agriculture.

For Abrão Neto, the conclusion of elections in both countries creates an opportunity to renew dialogue and seek better terms for bilateral trade.

Last week, U.S. Secretary of State Marco Rubio said there were “some trade issues” in the relationship with Brazil. “That also needs to be addressed,” he said. According to Rubio, U.S. Trade Representative Jamieson Greer is “working on that.”

As Valor reported, the Brazilian government had been waiting since last week for the U.S. to submit a proposal for a possible agreement. Brazil is expected to request the establishment of a panel at the World Trade Organization’s (WTO) Dispute Settlement Body.

At the same time, there is an expectation that a Democratic-controlled Congress will take up the tariff issue. U.S. analysts, however, have doubts about how far the new Congress will be able to go.

“Listening to what people in Washington have been saying so far, I’m disappointed. People are talking about small steps. Removing tariffs on Canada would be a more likely first step. But to me, that’s an obvious thing to do, and not particularly courageous—not in keeping with the encouraging election results,” said Mary Lovely, a researcher at the Peterson Institute for International Economics (PIIE) and professor emerita of economics at Syracuse University.

Eric Jacobsen, a researcher at the Inter-American Dialogue and a former Democratic adviser on Latin America and the Caribbean to the House Foreign Affairs Committee, noted that the U.S. Supreme Court blocked President Donald Trump from imposing tariffs under the IEEPA but left other avenues open for their implementation, including Section 301, which addresses allegedly unfair trade practices. “I think the president still has considerable room to maneuver,” he said.

Lovely said Congress is interested in reclaiming its authority over trade policy through reforms to existing procedures, including the use of Section 301 or Section 232, which concerns national security.

“Will they be able to get anywhere? That’s the big question, as changing these laws is difficult. One reason is that Congress has used them over time to push the executive branch to be more aggressive. Now, they want to strip those powers back. But what about the next president? Will they want that president to be more or less aggressive?” she asked.

Cullen Hendrix, also a researcher at PIIE, noted that Americans’ rejection of tariffs can also be understood in the context of the backlash against corruption that dominated this year’s elections. Tariffs were imposed unilaterally and transactionally, amid a strong perception that the policy was driven by the pursuit of personal interests, he said. For that reason, he believes Congress will use its power over the budget to restrict—or at least try to limit—the executive branch’s authority over tariffs.

Jacobsen, of the Inter-American Dialogue, said he expects Congress to pass legislation suspending certain tariffs, but believes Trump will probably veto it. The question, he said, is whether some Republicans in Congress will join Democrats in voting to override the vetoes.

“I would say that’s a challenging task. But given the current environment and voters’ concerns about the cost of living, which is directly linked to these tariffs, I don’t think Congress can’t get something done,” he said.

For Hendrix, even if Trump issues vetoes, the debate itself is significant because it forces the president to take an official position on issues that a Republican-controlled Congress might otherwise never have allowed to advance that far. It is a strategy of “blame-shifting,” he said: “The legislative majority sends a bill it knows will be vetoed, not with the genuine intention of negotiating, but to force the president to take an unpopular position.”

*By Anaïs Fernandes — Washington

Source: Valor International

https://valorinternational.globo.com/


TV Globo correspondent Sônia Bridi speaks at Conexão CMO event, hosted by Globo and Valor — Foto: Flavio Rodrigues/Divulgação
TV Globo correspondent Sônia Bridi speaks at Conexão CMO event, hosted by Globo and Valor — Photo: Flavio Rodrigues/Divulgação

A focus on product innovation, heavy investment in advertising, and playful marketing campaigns are among the cultural characteristics of East Asian companies helping them win over Brazilian consumers in sectors such as cosmetics, automobiles, beverages, and services.

The growing influence of East Asia also represents a business opportunity for Brazilian brands, according to a study titled “Asia in Motion,” presented on Thursday (12) at Conexão CMO, an event organized by Globo and Valor for marketing executives. “This trend has significant influence on the advertising market,” said Eliseu Barreira, Globo’s director of strategy and business intelligence, at the event. “The arrival of these new competitors, with different approaches to innovation, positioning, and communication, is also changing competitive dynamics and creating new benchmarks for companies from all backgrounds,” he added. Over the past 12 months, Chinese, Japanese, and South Korean companies spent R$3.2 billion on advertising in Brazil, a 16% increase from the previous year, Barreira noted.

Making products tangible, rather than simply promoting an idea or concept, is one of the distinctive features of East Asian brands’ advertising campaigns compared with those of Western companies, said Bruno Pompeu, a professor at the University of São Paulo’s School of Communications and Arts (ECA-USP) and coordinator of Casa Semio.

“Asian brands always keep the product at the center. You could talk only about a technological innovation, but it is important to remember that the product itself exists in the real world. That is something entirely new for people who were almost imagining that consumption was becoming dematerialized,” Pompeu said while presenting the study.

Another notable feature is the media strategy adopted by Asian cosmetics brands. “We found that they have built their audiences on social media, but they continue to invest heavily in points of sale, brand activation and what are traditionally considered conventional media,” the professor said. “They have a much more sophisticated understanding of how different media channels work together than we sometimes see here.”

Brazil is among the world’s 10 largest consumers of South Korean cosmetics. Brazilian imports of personal care, perfumery, and cosmetics products from South Korea nearly tripled in three years, reaching $34.6 million in 2025, according to the Brazilian Association of the Personal Hygiene, Perfumery, and Cosmetics Industry (Abihpec).

South Korean K-pop is a prominent example of how culture and consumption can be integrated, gaining widespread popularity in Brazil, as have Asian television dramas, commonly known as doramas. The Japanese adaptation of the word “drama” was added to the Portuguese-language dictionary in 2023.

The production values of East Asian television dramas have helped popularize the format, said journalist, author, and TV Globo special correspondent Sônia Bridi during a panel discussion at the event. Investments in culture and education in South Korea and China are examples of the pragmatic approach adopted by those countries’ governments, she said.

“South Korea invested in K-pop and K-drama production in the same way a country invests in a strategic industry such as oil production or the manufacturing of phones and televisions. In other words, there is a government-led strategy to project the country’s image abroad,” the journalist and documentary filmmaker said.

Bridi lived in Beijing for two years, from 2005 to 2006, where she and her husband, cinematographer Paulo Zero, established TV Globo’s first bureau in Asia. She recounted the experience in her 2008 book, “Laowai: Histórias de uma repórter brasileira na China” [literally, stories of a Brazilian reporter in China].

China’s innovation process initially involved copying products, but the country has since evolved, Bridi noted. She recalled deciding to buy a pickup truck from a Chinese brand that at the time was imitating a Western model. When a problem arose involving the jack mounting point, the company fixed it with a block of wood. “It was a great lesson for me—not about China’s backwardness, but about the Chinese ability to find solutions to problems,” the journalist said.

“Today I drive a fully electric car packed with technology, made by the same brand I bought from in China. I think that anecdote shows how, in 20 years, a company can go from imitating another brand, and not even doing a very good job of it, to becoming an innovative global brand,” Bridi said.

Collectivism is also a strong feature of East Asian cultures, including in education. Having followed the development of Chinese universities and their partnerships with American and European institutions, the documentary filmmaker noted that the choice of university major is also part of the government’s planning in China. “They have a lot of influence over what you study. It is not about what you want to be in life, but what the country needs,” she said. “Chinese leaders, for example, tend to come from polytechnic universities, while Western leaders are more likely to have studied law.”

A strong commitment to consumers is another important aspect of Chinese business culture. “In China, when you become someone’s customer, you become a friend, and they have an obligation to help you with any problem you may have,” Bridi said. The expansion of Chinese automakers in Brazil was also highlighted in the analysis of East Asian brands. Pompeu cited a BYD campaign that brought together 30 critics of the brand to test a new vehicle, borrowing the format of a public grilling that has become popular on social media. “They brought in 30 people who said they hated the brand and created a radio ad saying: ‘If you’re a BYD hater, watch out, because the new car is going to win you over,’” the professor said. “In the West, you don’t address your future customers as people who hate you. That is not the only way to approach consumers, but it suggests building a more candid relationship with them,” he said.

From January through October, Chinese brands accounted for 19.12% of passenger car and light commercial vehicle sales in Brazil, according to data from the National Federation of Motor Vehicle Distribution (Fenabrave).

(Bianca Guilherme contributed to this report)

*By Daniela Braun — São Paulo

Source: Valoar International

https://valorinternational.globo.com/


Banco do Brasil CEO Tarciana Medeiros acknowledged Thursday (Nov. 12) that the lender is facing one of the most severe periods of credit risk in its agricultural portfolio in more than 200 years of history. The crisis drove a 66.5% drop in third-quarter profit, sending the bank’s shares down 8.35% to R$15.48 and fueling analysts’ concerns about pressure on its capital position.

Medeiros sought to temper those concerns, stressing that Banco do Brasil’s business extends well beyond agriculture and that its net interest income remains strong. Still, there are few clear signs that earnings have bottomed out. The deterioration in agricultural credit forced the bank to set aside R$21.23 billion in provisions for loan losses between July and September.

The executive–who is considered unlikely to remain in her position during the next term of President Luiz Inácio Lula da Silva (Workers’ Party, PT)–insisted that Banco do Brasil (BB) had not been caught off guard and had been taking steps to address the agricultural crisis for nearly two years.

“As early as the first quarter of 2025, when we identified an unprecedented deviation from our expectations for timely payments in agriculture, we decided to suspend our guidance. When we reinstated it in the second quarter of 2025, we gave you a full assessment of what we were seeing at the time. As Brazil’s leading agricultural lender, we were the first to identify this trend as unusual,” Medeiros said.

Agricultural defaults

The bank’s agricultural loan delinquencies are “concentrated among medium-sized and large borrowers in soybean farming, corn production and cattle ranching, particularly in the Center-West,” Medeiros said.

Some of these producers deliberately failed to repay or renegotiate their debts even after the bank contacted them, behavior she described as “moral hazard.” BB also identified borrowers who appeared to be holding off on payments while awaiting the outcome of the elections.

“Last year, I pointed out that these defaults were a recent development among customers who had always paid on time. [Some] 85% of these customers became delinquent starting in 2024. Our response was intensive. We introduced a resilience matrix for new lending, reviewed our entire collateral framework, added fiduciary liens and completely overhauled our collections and recovery process.”

Under provisional presidential decree 1,376, the bank renegotiated R$13.4 billion in debt, falling short of the R$30 billion it had considered achievable.

Medeiros said BB had stepped up legal action and issued more than 20,000 out-of-court notices. Of the producers who received them, 24% subsequently contacted the bank to bring their accounts into good standing.

The lender also plans to begin selling portfolios of loans classified as losses to outside investors. Until now, such transactions had largely been conducted in bulk with Ativos S.A., a company owned by BB.

“We expect to gain traction very quickly,” Medeiros said.

Congress approved legislation converting the provisional decree into law this week. BB is awaiting presidential approval and any potential vetoes before assessing its impact, but sees the legislation as another opportunity to restructure troubled loans.

“For those who need help, there is a solution. […] For those who refuse to negotiate and do not pay, the response is debt collection,” she said.

Capital pressures

BB’s third-quarter net profit of R$1.27 billion heightened analysts’ concerns about the bank’s capital position.

Chief Financial Officer Geovanne Tobias acknowledged that those concerns “are legitimate” but said the lender had been closely monitoring the situation and taking action.

BB has identified more than 15 potential measures involving regulatory and corporate matters, although Tobias did not provide details.

“We naturally expect capital to strengthen organically as earnings improve throughout 2027.”

The bank projects a common equity Tier 1 (CET1) capital ratio of 10.5% at the end of next year. The ratio stood at 10.8% in September, down from 11.16% a year earlier.

Chief Risk Officer Felipe Prince said BB is not considering a scenario in which its capital ratio falls below 10%.

“The target is tight at 10.5%. We would like to be delivering 11%, but we are not working with a level below 10%,” Prince said.

To preserve capital, BB announced that it would cut its dividend payout ratio this year from 30% to the regulatory minimum of 25%. It also set a 25% payout ratio for 2027, provided that doing so remains consistent with its capital projections.

Tobias also mentioned the possibility of initial public offerings (IPOs) for companies within the BB group. Prince, however, said potential IPO proceeds were not included in the bank’s 2027 capital projections and would represent an additional benefit if they materialized.

Tax credits

Another measure under consideration involves converting deferred tax assets (DTAs) into presumed tax credits under an existing legal provision.

“The payment will be made by the Treasury, on its own timetable,” Tobias said.

The bank has between R$12 billion and R$14 billion in deferred tax assets eligible for conversion into presumed tax credits.

Tobias initially suggested the measure could boost the bank’s capital ratio by 1.2 percentage points, potentially as early as 2027. BB’s investor relations team later clarified that the estimated benefit would materialize over several years rather than entirely in 2027.

Analysts said the third-quarter results were significantly worse than expected, with continued credit deterioration raising doubts about when the bank might begin to recover.

Citi identified asset quality as the main concern, citing little evidence so far of a turning point.

“Overall, we see the quarter as clearly negative: earnings fell short of our already depressed expectations, asset quality deterioration continues to outweigh revenue resilience, and capital remains constrained. Importantly, the results still give us little reason to believe that credit trends have reached a turning point,” Citi’s analyst team wrote.

Tarciana Medeiros — Foto: Divulgação
                                                                                                                             Tarciana Medeiros — Photo: Divulgação

*By Lais Godinhoand Álvaro Campos, Valor — São Paulo
Source: Valor International
https://valorinternational.globo.com/


Brazilian Supreme Court Justice Flávio Dino rejected a request from retail, wholesale and manufacturing groups to delay the implementation of new working-hour rules that will end the six-day workweek under Constitutional Amendment 141. However, in a preliminary injunction, he allowed employers greater flexibility in scheduling days off, provided the arrangements are established through collective bargaining agreements.

The amendment reduces the standard workweek from 44 to 40 hours without cutting pay and guarantees two paid days off per week. The weekly limit will initially fall to 42 hours on Dec. 16 before dropping to 40 hours a year later.

In addition to easing restrictions on rest days, Dino ruled that during the transition period, which runs through Dec. 15, 2027, employers without collective bargaining agreements may spread the 42-hour workweek over five days, under a 5×2 schedule, with shifts of up to eight hours and 24 minutes without triggering overtime pay. Under Brazil’s Consolidation of Labor Laws (CLT), work exceeding eight hours a day normally requires overtime compensation.

The injunction, which must still be reviewed by the full Supreme Court, was issued in response to constitutional challenges filed by the National Confederation of Commerce in Goods, Services and Tourism (CNC) and the National Confederation of Industry (CNI). Both organizations had sought additional time to comply with the new rules (ADI 8041 and ADI 8042).

Flexibility on days off

On rest periods, Dino ruled that collective bargaining agreements may override the weekly requirement of two days off and the monthly requirement of eight days off. Employers could therefore grant just one day off in a given week, provided they preserve the eight monthly rest days. Under the injunction, even those eight days could be taken at a later date.

Retail and wholesale representatives raised the issue during a public hearing Tuesday (Nov. 10), citing the demands of the Christmas and New Year holiday season. In his ruling, Dino also pointed to other sectors that could be affected, including agriculture, where working schedules depend on planting and harvesting cycles; tourism and hospitality, which experience seasonal peaks; and offshore operations aboard vessels and platforms. Oil workers, for example, may work rotations of 90 days offshore followed by 90 days off.

“I believe these limits may be adjusted through collective bargaining agreements, provided the full entitlement to two paid weekly rest periods is preserved, even if their use is deferred,” Dino wrote.

The justice also granted unions and employers an additional 90 days, starting Dec. 16, to renegotiate any reciprocal concessions in existing collective bargaining agreements that may need to be revised because provisions conflicting with Amendment 141 will no longer be valid.

During that period, he said, a failure to reach a new agreement does not, in itself, justify eliminating previously negotiated concessions or changing them unilaterally.

Another significant provision gives Congress 180 days to regulate special working arrangements and establish implementation rules for microenterprises and small businesses. Dino also set a 180-day deadline for adapting public contracts to the new working-hour requirements, shortening the original one-year period.

Legal certainty during the transition

Labor law specialists say the decision to maintain the implementation timetable leaves companies facing a “very challenging” situation. Still, they believe the flexibility over rest days, the temporary authorization of eight-hour-and-24-minute shifts and the additional time for collective bargaining provide greater legal certainty during the transition.

Marcello Burle, a partner at law firm Martorelli Advogados, said the ruling offers “indispensable operational relief” by preventing companies from immediately accumulating overtime liabilities if they fail to conclude collective bargaining agreements by December.

“The injunction neutralizes the risk of bargaining deadlocks at the turn of the year and gives companies the predictability they need to redesign shifts and rebalance their collective agreements in an economically rational way during the first quarter of 2027,” Burle said.

Danilo Masko, of law firm Briganti Advogados, also highlighted the exemption from overtime pay for the additional 24 minutes worked each day.

“This prevents labor liabilities from arising solely because negotiations are taking longer,” he said, stressing that the provision is temporary and applies only to this specific situation, rather than granting blanket permission to extend working hours.

Because Dino’s ruling still requires approval by the full Supreme Court, Masko recommends that employers carefully document their new work schedules.

He also noted that the Supreme Court left the distribution of rest days to collective bargaining, without imposing weekly or monthly limits.

“However, the two paid weekly rest periods remain untouchable.”

José Eymard Loguercio, a partner at law firm LBS Advogados, which represents the Unified Workers’ Central (CUT), said preserving the timetable for reducing working hours was important. However, he warned that the flexibility granted for rest days “could create more problems than it solves” because the exemption was defined too broadly.

“The constitutional rule is mandatory. Any exception should be permitted only in exceptional circumstances justified by an inability to comply,” Loguercio said.

Flávio Dino — Foto: Rosinei Coutinho/STF
                                                                                                                          Flávio Dino — Photo: Rosinei Coutinho/STF

*By Beatriz Olivon, Valor — Brasilia
Source: Valor International
https://valorinternational.globo.com/
 

As part of the ongoing implementation of Brazil’s tax reform, the Federal Government issued Provisional Measure No. 1,399/2026, which sets out the rules governing the application of the Selective Tax (IS) and establishes the applicable rates.

The new tax, introduced by Constitutional Amendment No. 132/2023, will apply to motor vehicles, aircraft, watercraft, cigarettes and other smoking products, alcoholic beverages, sugar-sweetened beverages, and betting and lottery activities. The Provisional Measure also governs the taxation of extracted mineral products, which will be subject to a zero rate in 2027.

The Selective Tax serves a regulatory purpose by seeking to discourage the consumption and production of goods that are harmful to health and the environment. It has therefore become known as the “sin tax.”

Effective Date and Tax Rates

The Provisional Measure provides for the tax provisions to take effect on 2 February 2027, subject to the constitutional 90-day waiting period. Its progress through the National Congress warrants attention, particularly because proposed amendments may alter the text during the legislative process for its conversion into law.

The main rates provided for 2027 are 2.6% for sugar-sweetened beverages, 4.2% for malt beer, 8% to 24% for other alcoholic beverages, 66.7% plus BRL 3.50 per 20 cigarettes, 37.5% for other smoking products, 0.5% for betting and lottery activities, 6.8% for aircraft, and 12% for motorized watercraft. Passenger cars are subject to a base rate of 6.3%, which may be adjusted based on technical and environmental criteria. The measure also provides for zero or reduced rates for certain vehicles, aircraft, and watercraft, as well as tax relief for small producers of alcoholic beverages.

Tax Assessment and Compliance

The Provisional Measure sets out procedures for assisted tax assessment by the Brazilian Federal Revenue Service, formal acknowledgment of tax liabilities, and discharge of those liabilities through payment, split payment, or offset. It also establishes specific rules for imports. These provisions will require businesses to review and adapt their tax processes, internal controls, and tax risk management practices.

By Edson Colnaghi Neves, PhD

November 2026